New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
©PropTech Pulse 2025, All rights reserved.


India's real estate investment sector drew $18.6 billion in the first nine months of 2026, eclipsing the entire $14.2 billion recorded for last year. For long-time observers, this isn't a sudden spike. It's the maturation of a market moving from speculative housing purchases toward structured infrastructure and logistics assets.
The headline numbers tell a story of massive institutional confidence, but the detail reveals a sharper reality. Developer equity funding has contracted, residential capital flows have cooled, and foreign funds are chasing high-yield warehouses and data centres instead of generic apartment complexes. If you're allocating capital across these segments, understanding the divergence between wholesale deal-making and retail participation is the difference between catching a trend and buying into a bubble.
Real Estate Investment in India: Market Overview for 2026
Quick answer
India drew $18.6 billion in real estate capital through September 2026, surpassing last year's full-year total. Institutional players captured roughly 79% of Q3 deployment, heavily shifting weight toward data centres, warehousing, and commercial offices, while residential equity investment contracted sharply. Retail investors can tap into this cycle through publicly listed REITs, co-living platforms, and select metro micro-markets offering rental yields above 6%.
The numbers point to strong growth. Domestic institutions and foreign capital pushed transaction volumes past previous records. But what separates this cycle from earlier booms is asset quality.
Capital isn't sitting in unlisted flat projects anymore, waiting for prices to rise. Instead, investors deploy cash into income-generating assets backed by active tenants and clear exit routes.
Capital Inflows Hit Record Highs in 2026
From January through September, inbound real estate capital reached $18.6 billion, outpacing the $14.2 billion collected across the entire 2025 calendar year. The acceleration was particularly steep in the third quarter, which alone absorbed $9.5 billion according to market tracking reports. This quarterly figure represents the highest single-quarter absorption on record since India formalised cross-border real estate capital reporting.
The speed of deployment matters just as much as the absolute size of the pot. Institutions are rotating quickly from pre-construction speculation into stabilized assets. Funds that typically require eighteen months to negotiate deals are now executing within six to eight weeks.
This velocity squeezes margins for slower participants but firmly validates pricing floors in premium corridors.
Which Asset Classes Are Winning?
Office spaces and mixed-use developments continue to command over forty percent of total institutional allocation. However, the standout performer is data centres and associated digital infrastructure. Cloud expansion mandates, government digitisation pushes, and the entry of major hyperscalers have created a structural demand curve that traditional retail buyers rarely notice until ticket prices adjust.
Warehousing and logistics follow closely behind. E-commerce penetration in tier-two and tier-three cities has plateaued growth in urban warehouses, forcing capital southward toward Gujarat, Maharashtra's industrial belts, and Tamil Nadu's manufacturing zones.
Institutional vs. Retail: The Divergence in 2026
There is a growing gap between what big money buys and what individual investors hold. Understanding where that split happens prevents misreading the broader market health.
Why Foreign Money Flocked to Data Centres and Offices
Foreign capital contributed ninety percent of its Q3 allocation through US-based funds looking for inflation-hedged exposure in Asian markets. They aren't betting on simple price appreciation. Instead, they target cash-flowing assets secured by long-term service level agreements.
Tenants in data centres routinely lock in leases for seven to ten years. Office spaces follow suit, carrying pre-let commitments from technology firms and shared-workspace operators expanding their footprint well beyond Bangalore and Gurgaon.
Where Residential Investments Stand Right Now
Residential equity investment fell forty-three percent year-on-year in the first half of 2026, dropping to roughly $0.5 billion in tracked institutional deployment. Rising construction costs, moderating sales velocity, and tighter RBI lending norms dried up cheap bulk funding for wholesale developers.
Large capital pools now view speculative residential development as a liability rather than an opportunity. The retail housing market itself is not broken. Individual homebuyers still drive transactions through stage-wise consumer payments and standard bank disbursements.
| Sector | H1 2026 Share | Q3 2026 Trend / Driver |
|---|---|---|
| Office & Mixed-use | Over 40% of institutional deployment | Pre-let tech and healthcare leases stabilising valuations |
| Warehouses & Data Centres | Secondary focus area | Drove $9.5B Q3 surge; hyperscaler expansion fueling appetite |
| Residential Equity | Declining share amid developer caution | Down 43% YoY; shifted toward finished inventory to reduce risk |
| Logistics & Industrial Parks | Steady baseline inflow | Fueling secondary city migration as primary hubs saturate |
Best Ways to Invest in Real Estate as a Retail Investor in 2026
You do not need crores to participate in this cycle. The infrastructure that attracted institutional dollars also opened up smaller vehicle options. Here is how retail capital is positioning itself.
Investing in REITs and SM REITs
Maintenance REITs (SM REITs) launched specifically for builders faced slower adoption than expected because many promoters prioritized balance sheet repair over listing early. Nevertheless, operational commercial REITs like Embassy, Mindspace, and Brookfield deliver consistent dividend distributions. A listed REIT unit trades on stock exchanges, meaning you can enter or exit without waiting for a sale deed to register. Their underlying portfolio skews toward Grade A office parks with triple-net leases, cushioning against vacancy shocks.
Worked Example: REIT Dividend Versus Fixed Income Alternatives
Picture deploying ₹10,00,000 into a top-tier Indian commercial REIT that distributes a steady 9% annual return. That produces ₹90,000 yearly in passive cash flow. Contrast this with a AAA-rated corporate bond fund averaging 7.5% post-tax yield.
The REIT offers superior liquidity, inflation-linked rental escalations locked into tenant contracts, and upside if interest rates fall. You accept volatility instead. REIT units ride equity market waves rather than bonding quietly.
Plot Developments, Co-Living, and Warehouse Units
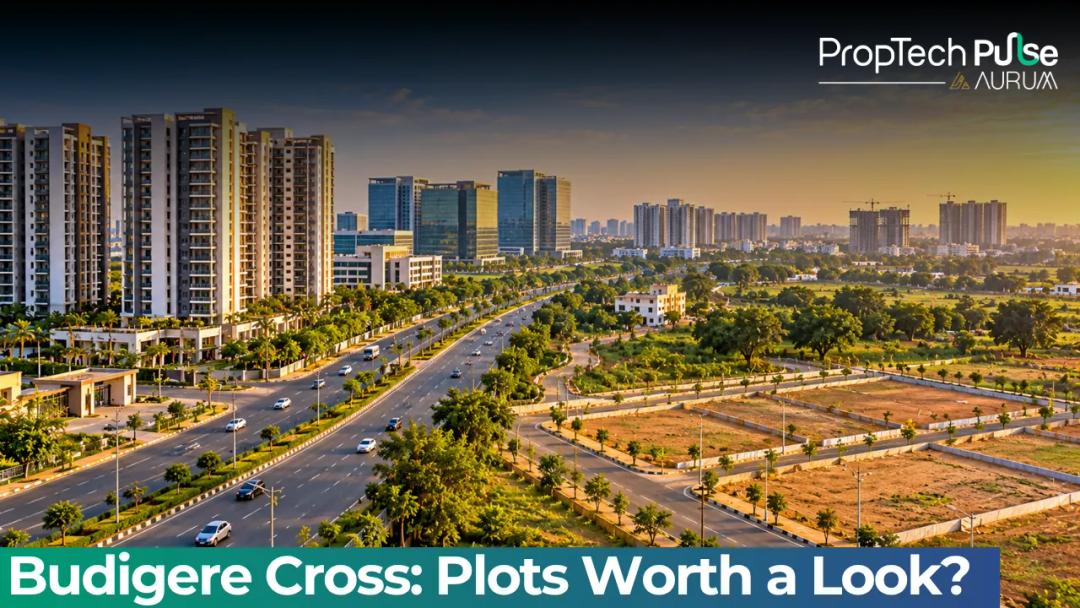
Plotted developments remain popular among upper-middle-class investors seeking control over land titles. These work best when located along emerging infrastructure corridors such as the Noida-Greater Noida Expressway or the Hosur Road belt in Bangalore. Verify that the layout plan has municipal approval and RERA registration before transferring any token amount. Unregistered plotted schemes expose buyers to prolonged encumbrance risks.
Co-living and affordable housing platforms appeal to investors who want regular yields without managing tenant disputes directly. Fractional ownership models let multiple buyers pool capital into a single high-value asset. Watch for fee structures. Heavy management charges can erode net returns faster than moderate occupancy dips.
Risk flag on warehouse conversions Converting agricultural land into industrial use requires state-specific zoning clearance and environmental approvals. Always confirm the site's conversion certificate and water availability before committing capital to rural-to-periurban warehouse plots.
Direct Home Buying for Rental Yield
Buying a flat for rental income still works, but the math has tightened. For those interested in investing in property, mature submarkets offer gross rental yields between 2.5% and 3.5%. In student-heavy micro-markets near medical colleges or engineering universities, you can push toward 5% to 6% if you furnish strategically and manage turnover efficiently.
Avoid taking on heavy debt to chase yield. A 70% loan-to-value ratio leaves little buffer for maintenance, property tax hikes, or vacant quarters.
Key Cities Attracting the Most Investment
Capital concentration remains heavy in established metros. Mumbai, Delhi-NCR, and Chennai together captured approximately fifty-three percent of all Q3 real estate investment deployment. Mumbai leads in institutional office portfolios and waterfront mixed-use redevelopment. Delhi-NCR benefits from airport adjacent logistics expansion and the sustained IT corridor lease activity. Chennai commands attention for manufacturing tie-ups and emerging data centre campuses in Tirupur and Sriperumbudur outskirts.
Hyderabad and Bengaluru sit just outside the top three but absorb capital at a faster compound annual growth rate. Both cities host overlapping demands for tech parks, affordable housing near transit nodes, and light industrial spaces serving cross-border e-commerce distribution.
Final Checklist: Is Real Estate Investment Right for You?
Before parking capital in either a REIT basket or a physical property, run your scenario through these filters:
- Tenure check: Can you hold for seven years minimum? Real estate rewards patient capital and penalises forced exits during micro-cycle downturns.
- Income versus appreciation: Define whether you want monthly yield or wealth building. Overlap often creates friction during maintenance spikes or valuation corrections.
- Micro-market validation: Look for visible infrastructure spend within five kilometres. New highways, metro extensions, or hospital approvals usually precede rent growth by eighteen to twenty-four months.
- Exit clarity: Physical properties require liquid secondary markets or transparent registry processes. Paper REITs or fractional platforms offer immediate liquidity but carry exchange volatility.
- Tax efficiency: Long term capital gains rules change periodically. Consult a CA to map holding period thresholds and stamp duty recovery allowances before adding real estate investment portfolios to your books.
Frequently asked questions
Is real estate a good investment in India 2026?
It depends on which segment you target. Core infrastructure assets like data centres and Grade-A offices offer stable yields backed by long leases. Residential buying works for end-users seeking wealth preservation rather than short-term flipping. Overall, the market rewards patience and disciplined micro-market selection over speculative timing.
Where is the highest real estate investment happening in India?
Mumbai, Delhi-NCR, and Chennai collectively absorbed over fifty percent of recent institutional deployment. Hyderabad and Bengaluru follow closely, driven by technology expansions and logistics corridors. Tier-2 cities like Pune and Ahmedabad gain traction when peripheral infrastructure upgrades reach completion milestones.
What are the safest real estate investment options for beginners in India?
Listed commercial REITs provide regulated disclosures, daily liquidity, and transparent dividend tracks without requiring property management skills. Alternatively, completed residential units in transit-oriented zones deliver predictable rents with lower execution risk. Avoid unlisted pre-launch equities or plot schemes lacking RERA certification.
Why are foreign investors investing heavily in Indian real estate now?
Global macro conditions favour hard-asset diversification away from overvalued Western commercial markets. India's regulatory clarity, scalable digital infrastructure, and domestic consumption growth create predictable cash flows. US-based capital alone contributed ninety percent of foreign deployment in Q3 2026, targeting data centres and warehouse networks with fixed-term tenant contracts.
How much do I need to invest in a REIT versus buying a flat?
REIT units trade like stocks, allowing fractional entry starting from a few thousand rupees depending on current market price. A single residential flat typically requires a twenty percent down payment plus registration costs, which often exceeds twenty lakh rupees even in affordable micro-markets. Choose REITs for flexible capital rotation. Buy direct property only if you can comfortably service mortgage debt and prioritise personal utility.
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.