Services
FOR BUYERS & RENTERS
FOR REAL ESTATE DEVELOPERS

Refer other Connectors &
Multiply IncomeRefer other Connectors
& Multiply Income
Refer KuberX & earn
commission on every
loan they get
disbursed.


Scan & Download
©PropTech Pulse 2025, All rights reserved.

What is Absolute Title?
Absolute Title in Real Estate
Absolute Title represents complete ownership of an asset with no other party asserting legitimate claims or liens. It signifies clear and uncontested rights to control and manage the property in any lawful manner, such as transferring it, leasing it out, or using it as collateral. This status assures both current and prospective stakeholders that no hidden interests exist, minimizing the likelihood of disputes or legal challenges.
Key Points
- Maximum Certainty: Owners face fewer complications in selling or financing.
- Minimal Risk: No active encumbrances reduce potential liabilities.
- Preferred by Buyers: Minimizes title concerns and eases transaction processes.
Having absolute title boosts confidence among lenders, insurers, and buyers, ensuring faster approvals or deals. Overall, it delivers a higher degree of security for anyone dealing with such an asset.
Recent Glossary
What are the benefits of z-score based property risk modeling?
What are the benefits of zakat calculation on real estate assets?
How is zero-emission construction equipment used in real estate?
How do zonal price index for urban housing markets work?
What is the meaning of zero-touch tenant onboarding technology?
View More...
Recent FAQs
How do construction firms use digital twins to plan phased renovations of an occupied building?
How do AR apps let buyers see a home's proposed solar panel layout before installation?
How do developers balance embodied carbon reduction with rising material costs?
What is a virtual open house and how does it differ from a live-streamed showing?
How do tokenization platforms handle inheritance when a token holder passes away?
View More...
Insight Pulse
Uncategorized
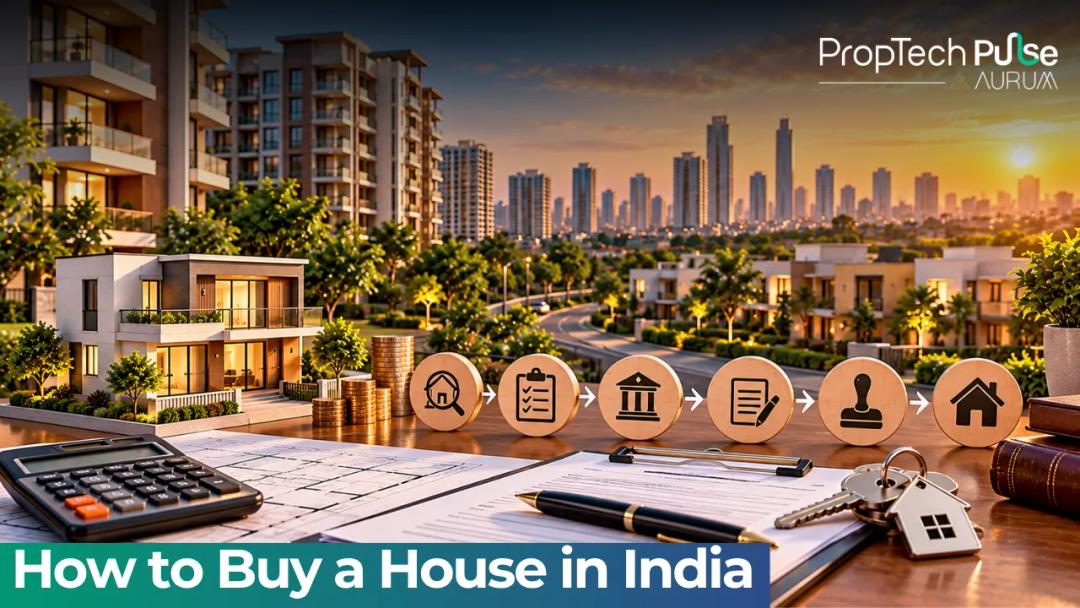
How to Buy a House in India: Step-by-Step Guide (2026)
Figuring out how to buy a house safely starts long before you view a single flat. The path demands patience and strict document handling. Focus on the safeguards protecting your capital, starting with the hidden costs that trip up seasoned investors. In this guide Assess your finances and set a realistic budget Shortlist properties and inspect the location Finalise the deal and secure the agreement Register the property and update records Summary: Your home-buying checklist Frequently asked questions Assess your finances and set a realistic budget Quick answer This guide shows how to buy a house without wrecking monthly cash flow. Focus on actual spending power rather than listing prices. Banks cap loans at five times yearly net pay, so factor in stamp duty, registration, and GST before requesting pre-approval. Ignoring upfront costs strains finances rapidly. Budgeting works backwards from the final price tag, not forwards from your salary. Many first-timers assume monthly installments handle everything. They don't. A ₹90 lakh flat demands liquid cash upfront for stamp duty, registration, GST, and legal checks before you pay the builder balance. Factor in hidden costs Competitors mention stamp duty but skip smaller line items adding thousands. Here is how upfront charges stack up across major cities as of September 2026: Average Stamp Duty and Registration Charges for Property Buyers Across Major Indian States (September 2026) State / City Stamp Duty (Men) Stamp Duty (Women) Registration Fee Maharashtra (Mumbai & Pune) 5% 5% (concessions vary) 1% Delhi NCR 6% 4% 1% Tamil Nadu (Chennai) 7% 7% 4% Uttar Pradesh (Noida, Lucknow) 7% 6% 1% Karnataka (Bengaluru) 5% 5% 1% Telangana (Hyderabad) 5% 5% 1% Gujarat (Ahmedabad) 6% 6% 1% Rajasthan (Jaipur) 7% 7% 1% Average Additional Cost on ₹80 Lakh Flat ₹4.8 lakh to ₹6.4 lakh + Registration GST applies strictly to under-construction projects while resale flats over five years escape this levy. Affordable units attract five percent rates, and luxury properties face twelve percent. Reserve extra funds for municipal taxes sellers shift to you before handing over keys. Cash buffer rule Never sign an Agreement to Sell if your liquid savings drop below twelve percent of the property value. That reserve covers legal checks, unexpected maintenance calls, and initial furnishing without forcing you into high-interest personal loans. Compare home loan offers and understand eligibility Rates typically sit between 7.15% and 8.75%, shifting based on your credit score and employer type. Banks weigh the Debt-to-Income ratio alongside the Fixed Obligations to Income Ratio (FOIR). Your total monthly outflow must stay capped at fifty-five percent of gross income. Pull a CIBIL score above 750 to secure the lowest slabs and quicker payouts. Scores between 650 and 749 trigger higher rates or bigger down-payment requests. Demand an Estimate of Remaining Charges (ERC) sheet beforehand. It exposes hidden processing fees, penalty clauses, and tenure tweaks that banks hide in the fine print. Shortlist properties and inspect the location Scrutinize locations with healthy skepticism. Livability dictates exit strategy. Proposed transit lines sound great until construction stalls for years. Target zones with functioning amenities today instead of relying on five-year masterplans. What to check during a site visit Builders dress model units with high-end finishes and spacious layouts. Those setups conceal structural flaws. Walk through your chosen apartment during a downpour and spot these red flags: Water logging or damp patches on ground-floor plinths or terrace edges. Weak natural light in the living room or bedrooms during midday (indicates poor ventilation). Excessive street noise bleeding through walls (ask to open windows facing the road). Uneven flooring tiles or mismatched grout lines (suggests rushed finishing). Measure carpet area against the brochure figures immediately. Carpet area captures usable inner space plus internal wall thickness. Super built-up area inflates the number by adding common zone shares like lobbies and stairs. RERA mandates sales based strictly on carpet area, meaning discrepancies exceeding four percent justify renegotiation. Verify the legal compliance and RERA registration [INTERNAL LINK: How to check if a builder is RERA registered] Verify compliance beyond standard paperwork. Your RERA registration number functions as a primary shield. Marketing projects or collecting advances without it remains illegal. Enter the project code into the state portal beforehand. Review launch dates and disciplinary histories. Cross-check approved blueprints against rising structures. Unauthorized floor additions instantly invalidate your insurance coverage. Finalise the deal and secure the agreement The Agreement to Sell sparks most ownership disputes. This document fixes final pricing, payment calendars, and deadlines. Demand milestone-linked disbursements for new builds. Tie funds to physical benchmarks like foundation pouring or slab casting. Work halts automatically freeze your payment liability. Audit penalty clauses meticulously. Developer possession delays must attract your home loan interest rate. Drafts routinely punish buyers while excusing builder delays. Write every verbal commitment about parks and clubhouses directly into the annexure. Verbal assurances carry zero legal weight. Register the property and update records Settle all outstanding dues and collect possession papers before visiting the Sub-Registrar. Bring fresh ID proofs, passport photos, the draft deed, the occupancy certificate, and paid challans. Staff will scan fingerprints and take photos to prevent proxy registrations. Pay stamp duty and registration fees via state portals before submitting the deed. The registrar returns your stamped document within forty-eight hours. Mutation updates land revenue records to reflect your name legally. Unupdated titles keep tax bills flowing to the former owner, creating severe liability gaps during emergencies. Summary: Your home-buying checklist Treat purchases as risk management. Verify paper trails before transferring funds. Track mutation updates strictly. Follow these steps and ownership transfers smoothly. Frequently asked questions What documents are required to buy a house in India? You need the title deed proving clean ownership history, an Encumbrance Certificate confirming zero outstanding loans, the approved building layout plan, and the Completion or Occupancy Certificate. Salaried applicants must supply Form 16, bank statements for the last six months, and latest IT returns. Buyers purchasing off-plan under-construction projects also require the builder's RERA certificate and the executed Agreement to Sell drafted by an independent property lawyer. How can I calculate my home loan eligibility? Lenders multiply your monthly gross salary by a standard multiplier, often twenty times, then subtract existing monthly debt obligations like credit card minimums or vehicle EMIs. The resulting net figure forms your Maximum EMI capacity. Ensure your total fixed commitments stay below fifty-five percent of your income, because banks reject applications that exceed this FOIR threshold during final underwriting checks. What is the difference between carpet area and super built-up area? Carpet area measures the exact usable square footage inside your apartment walls, including internal partition thickness. Super built-up area adds a proportional share of common zones such as elevators, stairs, gardens, and clubhouses. Under current RERA guidelines, developers must quote prices based solely on carpet area, making it the only metric that reflects genuine value for money. Is RERA registration mandatory for builders? Yes. Any residential project exceeding eight hundred square metres or containing more than eight apartments must register on your state Real Estate Regulatory Authority portal before marketing or collecting advances. Unregistered builders face heavy fines, project halt orders, and inability to lock in buyer payments through escrow accounts, leaving purchasers legally unprotected during construction delays. How long does the property registration process take? Physical presence at the Sub-Registrar office takes roughly three to four hours to complete biometric scans, document verification, and digital stamp affixing. Official document processing typically returns within forty-eight working days. Mutation of municipal land records follows separately and can take anywhere from thirty to ninety days depending on local administrative workloads and pending property tax clearance. Sources Aditya Birla Capital: State-wise stamp duty and registration fee tables (accessed September 2026) Visheshank: GST slabs, home loan interest ranges, and credit score thresholds (accessed September 2026) LT Finance: 2026 home buying process framework (accessed September 2026) PropertyPistol: Foundational steps and prerequisite overview (accessed September 2026) Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.

PropTech Pulse Editorial
10th October 2026
Uncategorized
Types of Residential Property in India: Complete Buying Guide
You’re looking at two dozen listings, trying to decide between a G+3 builder floor in Pune, a 3BHK high-rise in Bengaluru, and a standalone house in Noida Extension. The brochure calls them all “homes.” The registration charges differ. The maintenance bills don’t match. And the exit timeline varies wildly. This guide breaks down the actual types of residential property in India by format, ownership model and project stage. Understanding these options clarifies why registration fees jump unexpectedly. You will stop guessing. We show you exactly how to pick the right match for your budget. In this guide By Physical Format, Ownership Model and Stage How Each Property Type Impacts Your Monthly Costs Apartments vs Independent Houses vs Villas: When to Choose Which Quick Decision Rule: Pick Your Property Type in 3 Steps Frequently asked questions What Are the Main Types of Residential Property in India? Quick answer The main types include apartments, independent houses, villas, townhouses and builder floors. Your choice depends on three filters: the physical structure, the legal ownership model and the project stage. Apartments dominate city markets because land scarcity keeps driving prices up. By Physical Format Apartments and flats dominate urban supply. They share walls, a common entrance and basic amenities like security staff. High-rises optimise land cost but carry heavier monthly maintenance loads. Independent houses and bungalows give you exclusive control over the plot and building. You pay for every service separately. Water pumps, solar inverters and waste management raise your annual holding cost even if the purchase price matches a mid-tier flat. Villas and row houses sit between the two extremes. You own the ground floor and often upper levels within a gated community. Shared driveways, landscaping and perimeter walls bind neighbours together. Builder floors exist in the transition zone. A G+3 structure split across four separate units offers cheaper entry prices than mid-rise societies. Expect fewer shared amenities and minimal institutional governance beyond the managing committee. Penthouses crown the tower with larger footprints and higher ceilings. Rooftop access justifies premium pricing, but these units still rely on the parent building’s lift shaft and fire safety systems. Studios and duplexes serve niche needs. Studios target singles or young couples wanting a low base cost. Duplexes split a single unit vertically inside the same slab for privacy without a full independent house. By Ownership Model Freehold means you own the land and the structure indefinitely. State revenue rules apply, but most new gated communities operate on this model. Leasehold applies where the government retains land ownership. Delhi and parts of Gujarat use this tenure heavily. Ninety-nine year runs are standard. Rental goes to the government and renewals involve fresh payments depending on local law. Cooperative societies frame ownership through shares rather than title deeds. Membership rights cover the society’s block and plot. Selling requires board approval, which slows liquidity but checks speculative buying. Joint ownership usually follows marriage or inheritance. Two names appear on the sale deed. One typically holds majority voting power in the society, which matters when maintenance hikes spark disputes. By Project Stage Ready-to-move units arrive with occupancy certificates and finished interiors. You can visit the exact layout and test water pressure before signing. Risk sits entirely on the builder’s delivery track record. Under-construction projects offer lower entry prices and milestone-linked payment plans. RERA mandates dedicated escrow accounts for buyer funds. Possession delays averaging 113 days nationally remain a reality. [VERIFY current delay averages from latest World Bank or state RERA reports] Newly launched towers often sell units off-plan using 3D floor plans. Pricing locks early, but final carpet areas shift slightly once concrete hardens. Verify that the approved plan matches the showroom display. Resale flats bypass launch premiums entirely. Liquidity depends on locality demand and building age. Older societies sometimes struggle with loan eligibility if the property crosses the lender’s depreciation threshold. How Each Property Type Impacts Your Monthly Costs & Maintenance Purchase price is only half the equation. Holding costs dictate how comfortably you can live there while waiting for appreciation. Typical cost and suitability breakdown for common residential formats in major Indian cities, 2026 estimates Format Ideal For Avg Stamp Duty Impact* Maintenance Burden Typical Entry Price Bracket Apartment / Flat Metro professionals, families seeking amenities 5%–7% (state dependent) High (shared amenities, lifts, security) ₹40 lakh – ₹2 crore+ Independent House Multigenerational families, privacy seekers 6%–8% Low fixed, high variable (self-maintained) ₹60 lakh – ₹3 crore+ Villa / Row House NRI investors, long-stay buyers 5%–8% Medium (community society maintenance) ₹1.2 crore – ₹5 crore+ Builder Floor First-time buyers, cost-conscious families 5%–7% Low (minimal shared infrastructure) ₹30 lakh – ₹80 lakh Penthouse Luxury buyers, lifestyle-driven buyers 5%–7% + additional taxes Very high (premium AMC rates) ₹2.5 crore onwards *Stamp duty rates vary significantly by state and city classification. Verify local IGR thresholds before calculating total acquisition cost. You will notice the independent house looks cheaper on paper until you factor in municipal property tax and self-funded repairs. A cracked terrace slab or failing water membrane costs far more when warranties expire. You hold the entire bill then. Maintenance trap Avoid properties where the maintenance allocation exceeds ₹30 per square foot unless the society offers rental income potential, like commercial podium space or ample parking leasing. That figure leaves little margin for capital expenditure like roof waterproofing or lift modernisation. Apartments vs Independent Houses vs Villas: When to Choose Which Your location and risk appetite usually filter the field faster than price alone. Commuting costs erode savings faster than monthly maintenance does. Workplaces in Mumbai or Delhi NCR demand locations within walking distance of a metro line. Peripheral suburbs sell space at the expense of daily convenience. You can model the exact trade-off using our rent versus buy financial breakdown. Yield hunters typically target gated societies near expanding IT hubs. Corporate tenants provide steadier occupancy than older independent housings. Brokerage and stamp duty eat into gross returns before you even move in. Factor those expenses into our flat versus plot investment comparison. Quick Decision Rule: Pick Your Property Type in 3 Steps Step one: Lock your maximum monthly outgo. Add 1.5 times the expected EMI to cover property tax, maintenance and unexpected repairs. If the number forces you below a ₹70 lakh ticket price in your target city, look at builder floors or smaller flats. If the number supports ₹1.5 crore plus, you can entertain villas or larger independent plots. Step two: Match risk to timeline. Under-construction is viable if you can wait eighteen months or more and the developer holds a clean RERA registration. Visit our [INTERNAL LINK: RERA Registration Checker] to verify escrow compliance and past possession history. Steering clear of complex paperwork helps first-time buyers. Understanding the broader types of residential property upfront stops you from mismatching timelines later. Skip under-construction if you need a placement transfer within twelve months. Step three: Visualise the exit. Do you plan to stay ten years or more? Independent houses command steadier long-term appreciation in stable neighbourhoods. Land values grow faster than concrete structures. Apartment values ride on amenity upgrades and locational pull instead. Career moves within five years demand high-liquidity formats. Pick standard 2BHK or 3BHK layouts in societies with established reputations. ₹30–60 lakh ticket, low risk tolerance, 5-year exit → Builder floor or compact resale flat. ₹60–1.5 crore ticket, moderate risk, 7+ year hold → Ready-to-move apartment or low-density independent house. Above ₹1.5 crore ticket, high patience, luxury end-use → Gated villa or penthouse. Frequently asked questions What are the main types of residential property in India? They fall into six main formats. Apartments stack vertically in towers. Independent houses sit on private plots. Villas anchor gated communities. Townhouses share boundary walls. Builder floors occupy low-rise structures. Studios cater to singles. The layout directly shapes how much space you use daily and what maintenance falls on you. Difference between apartment and condominium in India? India does not use the term condominium widely for standard flats. In practical usage, a condominium refers to a project developed by multiple builders sharing a single large plot, similar to an apartment society but managed collectively. Legal titles function almost identically, though some states treat condo developers differently under local RERA frameworks. What is freehold vs leasehold property in India? Freehold gives you permanent ownership of both the building structure and the underlying land until you voluntarily sell it. Leasehold means the government or a designated authority owns the land while you hold the structure for a fixed period, typically ninety-nine years. Leaseholders pay periodic rent to the landowner and face renewal formalities. Which residential property is better for long-term investment? Independent houses generally deliver stronger capital appreciation over a decade because land values appreciate faster than built-up concrete structures. However, apartments offer quicker rental yields in metro hubs where tenant demand concentrates near corporate parks. Match the asset class to your target city’s growth corridor. Are builder floors cheaper than apartments? Builder floors usually carry a lower per-square-foot rate compared to mid-rise apartment towers in the same locality. The discount reflects the lack of expensive amenities like swimming pools, gyms and elaborate lobbies. Buyers accepting modest infrastructure often find builder floors offer faster ROI because the exit markup stays relatively thin. Sources Ken Research: India Residential Real Estate Market: Sales mix data, market size and permit delay averages (accessed September 2026) Reserve Bank of India (RBI): Housing affordability metrics and mortgage trends (accessed September 2026) Central Board of Indirect Taxes and Customs (CBIC): GST applicability and property transaction guidelines (accessed September 2026) Pradhan Mantri Awas Yojana (PMAY) Official Portal: Subsidy schemes and affordable housing push details (accessed September 2026) IGR Maharashtra / IGR Karnataka: State-wise stamp duty slabs and registration fee structures (accessed September 2026) Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
PropTech Pulse Editorial
10th October 2026
Uncategorized
Properties for sale in India 2026: Pricing shifts and strategic buying
Active searches for properties for sale today face inventory that looks nothing like the pre-2023 market. Entry-level launches under ₹50 lakh now sit at just 18% of pipeline volume in the top seven metros, forcing builders to push larger formats and ready-to-move units instead. You will need a stricter vetting process to separate genuine deals from inflated asking prices. In this guide Why the 'Properties for Sale' Market Has Shifted in 2026 Ready-to-Move vs Under-Construction Where to Find the Best Properties for Sale Right Now How to Vet Listings Without Getting Caught Out When to Actually Commit Frequently asked questions Why the 'Properties for Sale' Market Has Shifted in 2026 Quick answer The smartest entry points for properties for sale in 2026 are ready-to-move flats and projects in established Tier-2 cities. With GST dropping to zero on completed units and affordable launches collapsing, buyers get immediate occupancy, zero construction risk, and significant tax savings compared to under-construction inventory. Land costs now absorb between 40% and 55% of total project budgets in premium zones across major urban corridors. Builders can no longer cross-subsidize luxury floors with cheap ground-floor inventory to move volume. Add a documented 34% spike in construction input costs over recent cycles, and the baseline price for any new apartment has moved sharply higher. Even government-backed initiatives have had to adjust expectations. Schemes like the Janta Awaas Yojana Phase II in Delhi offer EWS flats only in the ₹34.86 lakh to ₹35.50 lakh range, excluding GST, reflecting the hard floor created by raw material inflation [SOURCE: magicbricks.com, Sept 2026]. Commercial vs Residential Property India: Yields & Risks shows how investor sentiment has followed a similar logic, preferring stabilized assets over speculative ground-breaking. For individual buyers, this shift dictates a much stricter selection process. You cannot afford to assume that a booking price today will hold until possession. Builder balance sheets are heavily concentrated in unsold inventory, meaning payment flexibility matters far more than headline discounts. Negotiate structured disbursements rather than chasing arbitrary percentage cuts. Ready-to-Move vs Under-Construction The most direct financial advantage for buyers this year comes from how GST applies to completed versus ongoing projects. Once a builder obtains a Completion Certificate, the flat becomes a finished product. At that point, the supply chain tax drops to zero. Under-construction residential units carry an effective GST rate of 5% spread across the duration of the build. Let us run the numbers on a standard mid-tier listing. Say the base price is ₹75,00,000. If you book under-construction, you lock in ₹75 lakh now. The actual cost inflates by 5% GST, adding ₹3,75,000 to the ledger. Your total cost becomes ₹78,75,000. You also continue paying home loan interest during the construction phase for a unit you cannot occupy. Buy a completed flat instead: base ₹75 lakh, plus 0% GST. You save ₹3.75 lakh instantly. You also gain a roof over your head, allowing you to either live rent-free or offset your EMI through rental income from day one. Financial and operational comparison: Under-Construction vs Ready-to-Move (RTM) Feature Under-Construction Ready-to-Move (Completed) GST Liability ~5% effective rate 0% after Completion Certificate Handover Timeline 18 to 36 months Immediate possession Capital Appreciation Risk High if project stalls Locked-in upon booking Rental Yield Overlap Zero during construction Rent covers EMI from month one Risk Profile Builder-dependent execution Low risk once RERA certificate is issued Cash Flow Impact (Base ₹75 Lakh) Total outflow ≈ ₹78.75 Lakh + EMI drain Total outflow ≈ ₹75 Lakh + immediate utility When evaluating properties for sale, prioritize buildings that have secured the completion certificate. The math favors the completed unit overwhelmingly, especially when construction delays routinely push timelines back by twelve to eighteen months. Always verify the latest OC status with the municipal corporation before signing any agreement, since statutory approvals sometimes trail physical completion by months. Where to Find the Best Properties for Sale Right Now Metro peripheries are absorbing most of the capital inflow, pushing standard two-bedroom homes past ₹1.2 crore even in satellite towns like Greater Noida West or the fringes of Thane. Tier-2 markets currently offer better fundamental economics. Cities like Indore, Jaipur, Coimbatore, and Kochi maintain lower land baselines and support healthier rental yields relative to ticket size. Government infrastructure spending has quietly redistributed demand. New airport terminals in Jaipur and Vizag, alongside dedicated freight corridors in Tamil Nadu, are pulling middle-income buyers away from saturated western Mumbai belts. A solid 2BHK in established micro-markets of Indore frequently sits between ₹45 lakh and ₹60 lakh while maintaining steady commercial demand nearby. Developers in these hubs compete on finish quality and location access rather than speculative future connectivity, which translates to tangible livability from day one. Rental vacancies remain tight because local employment growth outpaces housing completions. That structural mismatch keeps yields stable even when broader credit conditions tighten. Beyond purchase price, circle rates dictate your exit strategy. In cities like Jaipur and Kochi, government-mandated minimum values rarely diverge wildly from actual market transaction prices. This alignment prevents sudden capital gains shocks when you eventually sell. Conversely, peripheral metros often feature artificially suppressed circle rates for agricultural land that suddenly reclassify as commercial, leaving buyers holding illiquid plots or stalled titles. Stick to areas with updated land-use classifications verified directly at the district collector’s office. Realistic property acquisition bands by city tier (September 2026 estimates) City Category Entry-Level Range (Standard 2BHK) Premium Range (Large 4BHK / Luxury) Tier-1 Metro Core ₹1.5 crore – ₹2.5 crore+ ₹4 crore+ Tier-1 Metro Periphery ₹90 lakh – ₹1.4 crore ₹2 crore – ₹3.5 crore Tier-2 Capitals (Indore, Jaipur, Vizag, Kochi) ₹45 lakh – ₹65 lakh ₹90 lakh – ₹1.2 crore Emerging Tier-2 Townships ₹30 lakh – ₹45 lakh ₹60 lakh – ₹80 lakh Read our breakdown on What Is Rental Yield in India? Calculate It Right to assess these entry points properly. Tier-2 hubs present lower entry costs and tighter vacancy risks, making them structurally safer bets than heavily indebted metro satellites suffering from massive oversupply. When comparing locations, focus on proximity to existing IT parks, teaching hospitals, and logistics hubs rather than proposed highways that may take a decade to materialize. Actual rental demand follows jobs, not blueprints. How to Vet Listings Without Getting Caught Out Filtering thousands of listings requires discipline. Start by verifying the builder's RERA registration number against the state portal. Do not trust the logo printed in a glossy brochure. Request the latest RERA certificate directly from the sales office and check the committed possession dates for each phase. Note any extensions already approved by the regulator; repeated postponements signal cash flow strain long before the building visibly slows down. Next, calculate the carpet area yourself using the architect's floor plan. The usable indoor floor space divided by the total super built-up footprint should generally fall between 65% and 75% for modern high-rises. Anything dipping below 65% means you are subsidizing excessive wall thickness, elevator lobbies, and landscaped clubhouses at your own expense. Hold your ground on price if the location justifies it, but walk away immediately if the carpet area variance hurts your resale valuation later. Every developer claims superior amenity offerings, but standardized specifications across communities mean the differentiator comes down to finish quality, legal compliance, and maintenance records. Cross-check past project delivery speeds on RERA portals. Past performance predicts future handovers far better than marketing renders. Before transferring any funds, demand a fresh Encumbrance Certificate spanning at least thirty years. It reveals unregistered agreements, pending litigation, or hidden mortgage notes that sales agents deliberately omit. A clean EC costs a fraction of a lawyer's fee and saves months of escrow disputes. Pair this with a basic title search at the sub-registrar office to confirm the seller actually holds marketable rights. If documents show fractional ownership or unresolved inheritance claims, withdraw immediately regardless of how attractive the listing appears. Pre-booking verification checklist: Start with the RERA certificate. Measure the carpet area on the blueprint before proceeding. Confirm the Completion Certificate actually exists. Finally, ask for a bank statement tracking project collections over the past six months. When to Actually Commit If your priority is protecting capital and avoiding endless waiting periods, restrict your search to ready-to-move inventory and pre-owned resale units that have already been legally registered. These listings trade without GST penalties, eliminate builder default risk, and allow you to test the physical quality of the construction before handing over life savings. Resale transactions also bypass the initial depreciation hit that new launches suffer once possession begins. If you absolutely require a brand-new launch, restrict your exposure to large, publicly listed developers who operate across multiple cities. Single-state private entities face disproportionate pressure when credit tightens. Either path demands rigorous due diligence. The era of passive acceptance regarding pricing and square footage metrics is officially over. Verify your eligibility for central tax deductions early in the process, since claiming relief retroactively complicates filing and erodes net returns. Frequently asked questions How do I tell if a builder is genuinely selling a ready-to-move property or just marketing a delayed unit? Genuine ready-to-move homes will have a valid Completion Certificate issued by the local municipal authority and an Occupancy Certificate from the fire department. Check these documents before signing anything. Many developers advertise units as 'available immediately' while waiting for statutory approvals. If the certificates are missing, treat it as under-construction for tax purposes. What is the fair stamp duty and registration charge for most Indian states? Most states levy stamp duty between 5% and 7% of the property value, plus a registration fee of 1%. Maharashtra charges 5% for male buyers and 4% for women, with an additional metro cess in Mumbai and Pune. Several southern states have introduced concessions for first-time homebuyers or smaller units. Always verify the current slabs on your state's IGR website because these rates change annually. Can I negotiate the price heavily on properties listed as urgent sales? Urgency usually signals liquidity stress for the seller, whether that is an individual developer needing quick funds or an investor exiting early. However, prime locations rarely drop drastically. Focus your negotiation on payment terms rather than headline price. Developers may offer extended construction-linked plans or waive the token amount, which saves you financing costs over the lifecycle of the deal. How much carpet area should I expect in a newly launched apartment? Modern high-rise apartments typically deliver a carpet-to-super-built-up ratio between 65% and 75%. Older layouts sometimes hover around 60%, meaning you pay a premium for walls and common areas. RERA mandates that builders sell on carpet area only, so compare ratios side-by-side. A 1,000 sq ft super built-up unit offering only 620 sq ft carpet is financially inefficient compared to a competitor offering 720 sq ft. Are Tier-2 cities safer investments than metro satellites like Noida Extension or Kharghar? Tier-2 hubs like Jaipur, Kochi, and Indore present lower entry costs and historically tighter rental markets, reducing vacancy risk. Metro satellites attract huge infrastructure spending but suffer from massive oversupply, making exits difficult for years. If your goal is steady rental yield and gradual appreciation, Tier-2 capitals currently offer better capital efficiency. Stick to established micro-markets near existing commercial corridors in both scenarios. Sources eDarpan: Premium Housing India 2026: Market share data on sub-₹50 lakh launches (accessed September 2026) eDarpan: Construction Cost Impact on Home Prices: Data on input cost spikes and GST implications (accessed September 2026) Magicbricks: Janta Awaas Yojana Pricing Update: EWS flat pricing benchmarks (accessed September 2026) Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
PropTech Pulse Editorial
10th October 2026
Uncategorized
How to Buy a House in India: Step-by-Step Guide (2026)
Figuring out how to buy a house safely starts long before you view a single flat. The path demands patience and strict document handling. Focus on the safeguards protecting your capital, starting with the hidden costs that trip up seasoned investors. In this guide Assess your finances and set a realistic budget Shortlist properties and inspect the location Finalise the deal and secure the agreement Register the property and update records Summary: Your home-buying checklist Frequently asked questions Assess your finances and set a realistic budget Quick answer This guide shows how to buy a house without wrecking monthly cash flow. Focus on actual spending power rather than listing prices. Banks cap loans at five times yearly net pay, so factor in stamp duty, registration, and GST before requesting pre-approval. Ignoring upfront costs strains finances rapidly. Budgeting works backwards from the final price tag, not forwards from your salary. Many first-timers assume monthly installments handle everything. They don't. A ₹90 lakh flat demands liquid cash upfront for stamp duty, registration, GST, and legal checks before you pay the builder balance. Factor in hidden costs Competitors mention stamp duty but skip smaller line items adding thousands. Here is how upfront charges stack up across major cities as of September 2026: Average Stamp Duty and Registration Charges for Property Buyers Across Major Indian States (September 2026) State / City Stamp Duty (Men) Stamp Duty (Women) Registration Fee Maharashtra (Mumbai & Pune) 5% 5% (concessions vary) 1% Delhi NCR 6% 4% 1% Tamil Nadu (Chennai) 7% 7% 4% Uttar Pradesh (Noida, Lucknow) 7% 6% 1% Karnataka (Bengaluru) 5% 5% 1% Telangana (Hyderabad) 5% 5% 1% Gujarat (Ahmedabad) 6% 6% 1% Rajasthan (Jaipur) 7% 7% 1% Average Additional Cost on ₹80 Lakh Flat ₹4.8 lakh to ₹6.4 lakh + Registration GST applies strictly to under-construction projects while resale flats over five years escape this levy. Affordable units attract five percent rates, and luxury properties face twelve percent. Reserve extra funds for municipal taxes sellers shift to you before handing over keys. Cash buffer rule Never sign an Agreement to Sell if your liquid savings drop below twelve percent of the property value. That reserve covers legal checks, unexpected maintenance calls, and initial furnishing without forcing you into high-interest personal loans. Compare home loan offers and understand eligibility Rates typically sit between 7.15% and 8.75%, shifting based on your credit score and employer type. Banks weigh the Debt-to-Income ratio alongside the Fixed Obligations to Income Ratio (FOIR). Your total monthly outflow must stay capped at fifty-five percent of gross income. Pull a CIBIL score above 750 to secure the lowest slabs and quicker payouts. Scores between 650 and 749 trigger higher rates or bigger down-payment requests. Demand an Estimate of Remaining Charges (ERC) sheet beforehand. It exposes hidden processing fees, penalty clauses, and tenure tweaks that banks hide in the fine print. Shortlist properties and inspect the location Scrutinize locations with healthy skepticism. Livability dictates exit strategy. Proposed transit lines sound great until construction stalls for years. Target zones with functioning amenities today instead of relying on five-year masterplans. What to check during a site visit Builders dress model units with high-end finishes and spacious layouts. Those setups conceal structural flaws. Walk through your chosen apartment during a downpour and spot these red flags: Water logging or damp patches on ground-floor plinths or terrace edges. Weak natural light in the living room or bedrooms during midday (indicates poor ventilation). Excessive street noise bleeding through walls (ask to open windows facing the road). Uneven flooring tiles or mismatched grout lines (suggests rushed finishing). Measure carpet area against the brochure figures immediately. Carpet area captures usable inner space plus internal wall thickness. Super built-up area inflates the number by adding common zone shares like lobbies and stairs. RERA mandates sales based strictly on carpet area, meaning discrepancies exceeding four percent justify renegotiation. Verify the legal compliance and RERA registration [INTERNAL LINK: How to check if a builder is RERA registered] Verify compliance beyond standard paperwork. Your RERA registration number functions as a primary shield. Marketing projects or collecting advances without it remains illegal. Enter the project code into the state portal beforehand. Review launch dates and disciplinary histories. Cross-check approved blueprints against rising structures. Unauthorized floor additions instantly invalidate your insurance coverage. Finalise the deal and secure the agreement The Agreement to Sell sparks most ownership disputes. This document fixes final pricing, payment calendars, and deadlines. Demand milestone-linked disbursements for new builds. Tie funds to physical benchmarks like foundation pouring or slab casting. Work halts automatically freeze your payment liability. Audit penalty clauses meticulously. Developer possession delays must attract your home loan interest rate. Drafts routinely punish buyers while excusing builder delays. Write every verbal commitment about parks and clubhouses directly into the annexure. Verbal assurances carry zero legal weight. Register the property and update records Settle all outstanding dues and collect possession papers before visiting the Sub-Registrar. Bring fresh ID proofs, passport photos, the draft deed, the occupancy certificate, and paid challans. Staff will scan fingerprints and take photos to prevent proxy registrations. Pay stamp duty and registration fees via state portals before submitting the deed. The registrar returns your stamped document within forty-eight hours. Mutation updates land revenue records to reflect your name legally. Unupdated titles keep tax bills flowing to the former owner, creating severe liability gaps during emergencies. Summary: Your home-buying checklist Treat purchases as risk management. Verify paper trails before transferring funds. Track mutation updates strictly. Follow these steps and ownership transfers smoothly. Frequently asked questions What documents are required to buy a house in India? You need the title deed proving clean ownership history, an Encumbrance Certificate confirming zero outstanding loans, the approved building layout plan, and the Completion or Occupancy Certificate. Salaried applicants must supply Form 16, bank statements for the last six months, and latest IT returns. Buyers purchasing off-plan under-construction projects also require the builder's RERA certificate and the executed Agreement to Sell drafted by an independent property lawyer. How can I calculate my home loan eligibility? Lenders multiply your monthly gross salary by a standard multiplier, often twenty times, then subtract existing monthly debt obligations like credit card minimums or vehicle EMIs. The resulting net figure forms your Maximum EMI capacity. Ensure your total fixed commitments stay below fifty-five percent of your income, because banks reject applications that exceed this FOIR threshold during final underwriting checks. What is the difference between carpet area and super built-up area? Carpet area measures the exact usable square footage inside your apartment walls, including internal partition thickness. Super built-up area adds a proportional share of common zones such as elevators, stairs, gardens, and clubhouses. Under current RERA guidelines, developers must quote prices based solely on carpet area, making it the only metric that reflects genuine value for money. Is RERA registration mandatory for builders? Yes. Any residential project exceeding eight hundred square metres or containing more than eight apartments must register on your state Real Estate Regulatory Authority portal before marketing or collecting advances. Unregistered builders face heavy fines, project halt orders, and inability to lock in buyer payments through escrow accounts, leaving purchasers legally unprotected during construction delays. How long does the property registration process take? Physical presence at the Sub-Registrar office takes roughly three to four hours to complete biometric scans, document verification, and digital stamp affixing. Official document processing typically returns within forty-eight working days. Mutation of municipal land records follows separately and can take anywhere from thirty to ninety days depending on local administrative workloads and pending property tax clearance. Sources Aditya Birla Capital: State-wise stamp duty and registration fee tables (accessed September 2026) Visheshank: GST slabs, home loan interest ranges, and credit score thresholds (accessed September 2026) LT Finance: 2026 home buying process framework (accessed September 2026) PropertyPistol: Foundational steps and prerequisite overview (accessed September 2026) Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
PropTech Pulse Editorial
10th October 2026
Uncategorized
Types of Residential Property in India: Complete Buying Guide
You’re looking at two dozen listings, trying to decide between a G+3 builder floor in Pune, a 3BHK high-rise in Bengaluru, and a standalone house in Noida Extension. The brochure calls them all “homes.” The registration charges differ. The maintenance bills don’t match. And the exit timeline varies wildly. This guide breaks down the actual types of residential property in India by format, ownership model and project stage. Understanding these options clarifies why registration fees jump unexpectedly. You will stop guessing. We show you exactly how to pick the right match for your budget. In this guide By Physical Format, Ownership Model and Stage How Each Property Type Impacts Your Monthly Costs Apartments vs Independent Houses vs Villas: When to Choose Which Quick Decision Rule: Pick Your Property Type in 3 Steps Frequently asked questions What Are the Main Types of Residential Property in India? Quick answer The main types include apartments, independent houses, villas, townhouses and builder floors. Your choice depends on three filters: the physical structure, the legal ownership model and the project stage. Apartments dominate city markets because land scarcity keeps driving prices up. By Physical Format Apartments and flats dominate urban supply. They share walls, a common entrance and basic amenities like security staff. High-rises optimise land cost but carry heavier monthly maintenance loads. Independent houses and bungalows give you exclusive control over the plot and building. You pay for every service separately. Water pumps, solar inverters and waste management raise your annual holding cost even if the purchase price matches a mid-tier flat. Villas and row houses sit between the two extremes. You own the ground floor and often upper levels within a gated community. Shared driveways, landscaping and perimeter walls bind neighbours together. Builder floors exist in the transition zone. A G+3 structure split across four separate units offers cheaper entry prices than mid-rise societies. Expect fewer shared amenities and minimal institutional governance beyond the managing committee. Penthouses crown the tower with larger footprints and higher ceilings. Rooftop access justifies premium pricing, but these units still rely on the parent building’s lift shaft and fire safety systems. Studios and duplexes serve niche needs. Studios target singles or young couples wanting a low base cost. Duplexes split a single unit vertically inside the same slab for privacy without a full independent house. By Ownership Model Freehold means you own the land and the structure indefinitely. State revenue rules apply, but most new gated communities operate on this model. Leasehold applies where the government retains land ownership. Delhi and parts of Gujarat use this tenure heavily. Ninety-nine year runs are standard. Rental goes to the government and renewals involve fresh payments depending on local law. Cooperative societies frame ownership through shares rather than title deeds. Membership rights cover the society’s block and plot. Selling requires board approval, which slows liquidity but checks speculative buying. Joint ownership usually follows marriage or inheritance. Two names appear on the sale deed. One typically holds majority voting power in the society, which matters when maintenance hikes spark disputes. By Project Stage Ready-to-move units arrive with occupancy certificates and finished interiors. You can visit the exact layout and test water pressure before signing. Risk sits entirely on the builder’s delivery track record. Under-construction projects offer lower entry prices and milestone-linked payment plans. RERA mandates dedicated escrow accounts for buyer funds. Possession delays averaging 113 days nationally remain a reality. [VERIFY current delay averages from latest World Bank or state RERA reports] Newly launched towers often sell units off-plan using 3D floor plans. Pricing locks early, but final carpet areas shift slightly once concrete hardens. Verify that the approved plan matches the showroom display. Resale flats bypass launch premiums entirely. Liquidity depends on locality demand and building age. Older societies sometimes struggle with loan eligibility if the property crosses the lender’s depreciation threshold. How Each Property Type Impacts Your Monthly Costs & Maintenance Purchase price is only half the equation. Holding costs dictate how comfortably you can live there while waiting for appreciation. Typical cost and suitability breakdown for common residential formats in major Indian cities, 2026 estimates Format Ideal For Avg Stamp Duty Impact* Maintenance Burden Typical Entry Price Bracket Apartment / Flat Metro professionals, families seeking amenities 5%–7% (state dependent) High (shared amenities, lifts, security) ₹40 lakh – ₹2 crore+ Independent House Multigenerational families, privacy seekers 6%–8% Low fixed, high variable (self-maintained) ₹60 lakh – ₹3 crore+ Villa / Row House NRI investors, long-stay buyers 5%–8% Medium (community society maintenance) ₹1.2 crore – ₹5 crore+ Builder Floor First-time buyers, cost-conscious families 5%–7% Low (minimal shared infrastructure) ₹30 lakh – ₹80 lakh Penthouse Luxury buyers, lifestyle-driven buyers 5%–7% + additional taxes Very high (premium AMC rates) ₹2.5 crore onwards *Stamp duty rates vary significantly by state and city classification. Verify local IGR thresholds before calculating total acquisition cost. You will notice the independent house looks cheaper on paper until you factor in municipal property tax and self-funded repairs. A cracked terrace slab or failing water membrane costs far more when warranties expire. You hold the entire bill then. Maintenance trap Avoid properties where the maintenance allocation exceeds ₹30 per square foot unless the society offers rental income potential, like commercial podium space or ample parking leasing. That figure leaves little margin for capital expenditure like roof waterproofing or lift modernisation. Apartments vs Independent Houses vs Villas: When to Choose Which Your location and risk appetite usually filter the field faster than price alone. Commuting costs erode savings faster than monthly maintenance does. Workplaces in Mumbai or Delhi NCR demand locations within walking distance of a metro line. Peripheral suburbs sell space at the expense of daily convenience. You can model the exact trade-off using our rent versus buy financial breakdown. Yield hunters typically target gated societies near expanding IT hubs. Corporate tenants provide steadier occupancy than older independent housings. Brokerage and stamp duty eat into gross returns before you even move in. Factor those expenses into our flat versus plot investment comparison. Quick Decision Rule: Pick Your Property Type in 3 Steps Step one: Lock your maximum monthly outgo. Add 1.5 times the expected EMI to cover property tax, maintenance and unexpected repairs. If the number forces you below a ₹70 lakh ticket price in your target city, look at builder floors or smaller flats. If the number supports ₹1.5 crore plus, you can entertain villas or larger independent plots. Step two: Match risk to timeline. Under-construction is viable if you can wait eighteen months or more and the developer holds a clean RERA registration. Visit our [INTERNAL LINK: RERA Registration Checker] to verify escrow compliance and past possession history. Steering clear of complex paperwork helps first-time buyers. Understanding the broader types of residential property upfront stops you from mismatching timelines later. Skip under-construction if you need a placement transfer within twelve months. Step three: Visualise the exit. Do you plan to stay ten years or more? Independent houses command steadier long-term appreciation in stable neighbourhoods. Land values grow faster than concrete structures. Apartment values ride on amenity upgrades and locational pull instead. Career moves within five years demand high-liquidity formats. Pick standard 2BHK or 3BHK layouts in societies with established reputations. ₹30–60 lakh ticket, low risk tolerance, 5-year exit → Builder floor or compact resale flat. ₹60–1.5 crore ticket, moderate risk, 7+ year hold → Ready-to-move apartment or low-density independent house. Above ₹1.5 crore ticket, high patience, luxury end-use → Gated villa or penthouse. Frequently asked questions What are the main types of residential property in India? They fall into six main formats. Apartments stack vertically in towers. Independent houses sit on private plots. Villas anchor gated communities. Townhouses share boundary walls. Builder floors occupy low-rise structures. Studios cater to singles. The layout directly shapes how much space you use daily and what maintenance falls on you. Difference between apartment and condominium in India? India does not use the term condominium widely for standard flats. In practical usage, a condominium refers to a project developed by multiple builders sharing a single large plot, similar to an apartment society but managed collectively. Legal titles function almost identically, though some states treat condo developers differently under local RERA frameworks. What is freehold vs leasehold property in India? Freehold gives you permanent ownership of both the building structure and the underlying land until you voluntarily sell it. Leasehold means the government or a designated authority owns the land while you hold the structure for a fixed period, typically ninety-nine years. Leaseholders pay periodic rent to the landowner and face renewal formalities. Which residential property is better for long-term investment? Independent houses generally deliver stronger capital appreciation over a decade because land values appreciate faster than built-up concrete structures. However, apartments offer quicker rental yields in metro hubs where tenant demand concentrates near corporate parks. Match the asset class to your target city’s growth corridor. Are builder floors cheaper than apartments? Builder floors usually carry a lower per-square-foot rate compared to mid-rise apartment towers in the same locality. The discount reflects the lack of expensive amenities like swimming pools, gyms and elaborate lobbies. Buyers accepting modest infrastructure often find builder floors offer faster ROI because the exit markup stays relatively thin. Sources Ken Research: India Residential Real Estate Market: Sales mix data, market size and permit delay averages (accessed September 2026) Reserve Bank of India (RBI): Housing affordability metrics and mortgage trends (accessed September 2026) Central Board of Indirect Taxes and Customs (CBIC): GST applicability and property transaction guidelines (accessed September 2026) Pradhan Mantri Awas Yojana (PMAY) Official Portal: Subsidy schemes and affordable housing push details (accessed September 2026) IGR Maharashtra / IGR Karnataka: State-wise stamp duty slabs and registration fee structures (accessed September 2026) Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
PropTech Pulse Editorial
10th October 2026
Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.