New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
©PropTech Pulse 2025, All rights reserved.


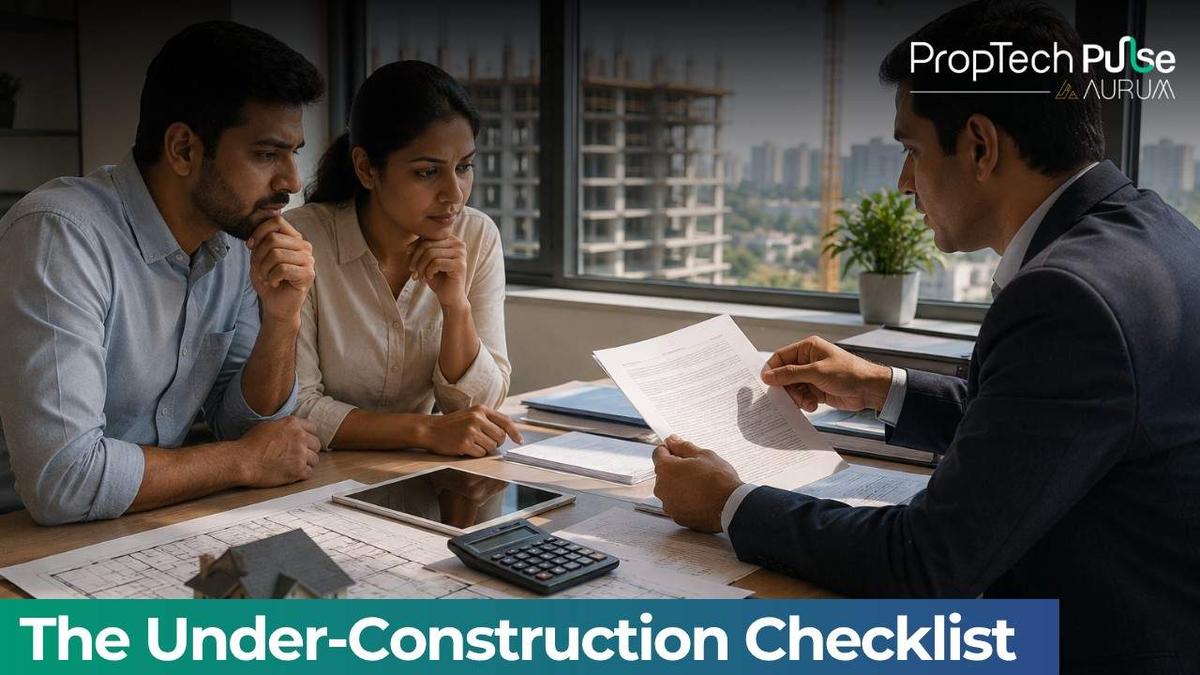
Three to four years is a long time to trust a promise. That's roughly the gap between signing for an under-construction flat and actually getting the keys, and in that window, a lot can go wrong that no brochure ever mentions.
Bank due diligence isn't the same as your due diligence
Banks check enough to protect their own loan exposure. They're not checking enough to protect you. A bank's due diligence typically confirms title is clean enough to lend against and that the project has basic regulatory approvals, but it won't flag clauses buried in your sale agreement that disadvantage you specifically, won't assess construction quality beyond what's needed for disbursement, and won't tell you whether the builder has a history of delayed handovers on prior projects. An independent property lawyer, engaged before signing rather than after a dispute starts, is worth the fee specifically because their incentives align with yours rather than the lender's.
Agreement clauses that deserve real scrutiny
The fine print that actually matters rarely gets read carefully. Possession timeline clauses should specify a firm date with genuine penalty provisions for delay, not vague language about "approximate" completion. Carpet area versus super built-up area definitions should be explicit, since the gap between the two is where a lot of promised square footage quietly disappears. Payment schedule structures tied to construction milestones protect buyers better than upfront-heavy schedules, and any clause allowing the builder to unilaterally alter specifications, layouts or amenities after signing deserves a hard conversation before you agree to it.
Landowner-share units carry a different risk profile
Units built under a landowner-share arrangement, where the original landowner receives a portion of constructed units in exchange for the land, can genuinely offer better pricing. But they come with a distinct verification requirement: buyers need to confirm the landowner's title independently of the builder's own paperwork, check whether the landowner-share units carry the same construction quality and specifications as builder-share units, and verify there's no dispute between the landowner and developer that could stall the project. Resale on these units can also be marginally harder if buyers in the secondary market are less familiar with the landowner-share structure and view it with unwarranted suspicion.
The cash component trade-off, plainly
Deals offering a discount for a 10 to 20% cash component are structured to reduce the registered sale value, which lowers stamp duty and registration costs, but it comes with real downstream costs. It reduces your loan eligibility since banks only finance against the registered value, creates a genuine tax exposure if the transaction is ever scrutinised, and significantly weakens your negotiating and resale position later, since the actual price you paid and the record price won't match. For a self-use purchase meant to be a long-term home, the legal and resale complications this creates generally outweigh the upfront saving.
What to verify about the construction itself
Beyond the sales pitch, ask for the sanctioned building plan and cross-check it against what's actually being marketed, since deviations are more common than buyers assume. Verify water source and storage capacity independently, particularly in peripheral areas where municipal supply is inconsistent, and don't rely on the sales team's assurances about "24/7 water" without checking the underlying infrastructure. Request the RERA registration number and read the disclosed project timeline and any recorded complaints directly on the state RERA portal rather than taking the builder's summary at face value.
The peripheral area bet is a genuine gamble, not a guarantee
Buying in a developing corridor near an established employment belt, betting that infrastructure catches up over three to four years, has worked out for plenty of Bengaluru buyers over the past decade, and has also left others stuck in areas where roads, water and traffic infrastructure lagged well behind the promised timeline. The honest answer is that this bet depends heavily on which specific pocket you're in and how committed local authorities actually are to funding the connecting infrastructure, not just announcing it. Buyers making this bet should treat the "3-4 years, and it'll be fine" assumption as a hope, not a plan, and be genuinely comfortable with the area as it exists today, not just as it's projected to become.
On loan structuring
An overdraft-linked home loan structure can meaningfully reduce interest outgo if you genuinely have surplus funds to park against the loan consistently, since interest is calculated on the net outstanding balance rather than the full loan amount. Whether it's worth the typically higher interest rate premium these products carry depends entirely on how much you can realistically keep parked and how disciplined you'll actually be about it over years, not just in the first few months of enthusiasm.
Enjoyed this update? Visit PropTech Pulse for more real estate news and market insights.


