New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
Services
FOR BUYERS & RENTERS
FOR REAL ESTATE DEVELOPERS

Refer other Connectors &
Multiply IncomeRefer other Connectors
& Multiply Income
Refer KuberX & earn
commission on every
loan they get
disbursed.


Scan & Download
©PropTech Pulse 2025, All rights reserved.


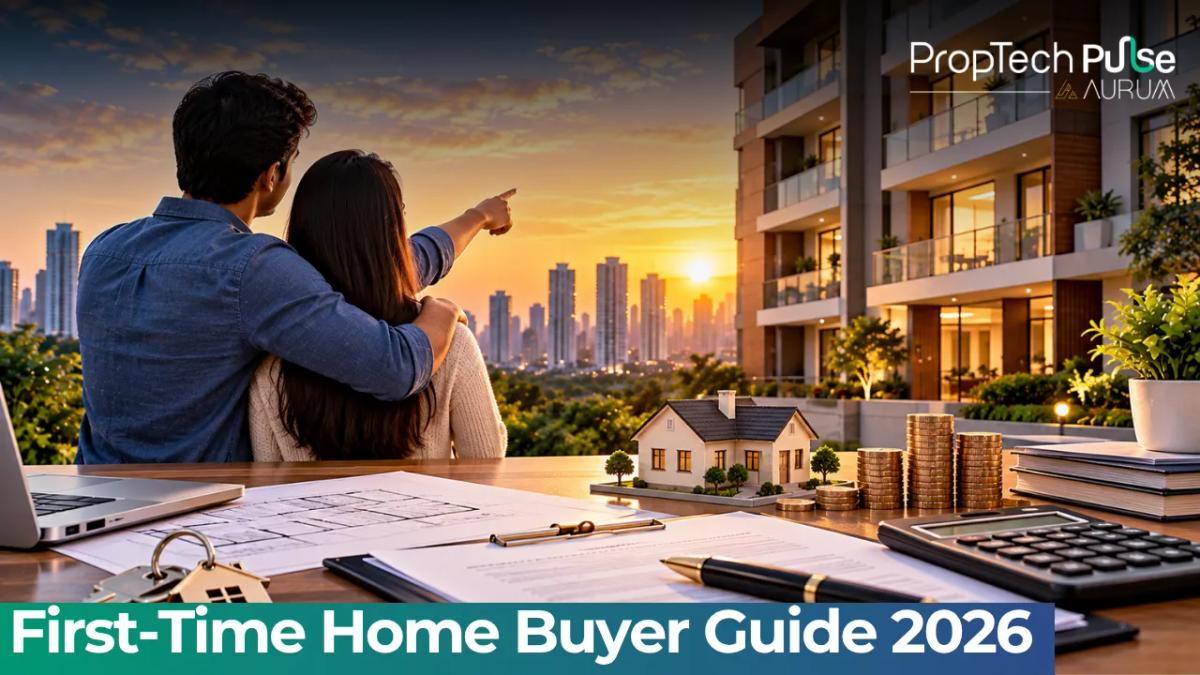
Buying your first home in India is a massive commitment. A first time home buyer usually walks away from the site visit with two unpleasant surprises. The first is the hidden costs that tack another 8% to 12% onto the flat's sticker price. The second is picking a lender based on a headline interest rate while paying thousands more in processing fees and locked-in tenures.
This guide walks through the full process. You will find a phase-by-phase roadmap, the cash you actually need upfront, how to compare 2026 loan offers, and when government subsidies like PMAY 2.0 make sense. Everything is based on the rates and rules current as of September 2026.
Who Qualifies as a First Time Home Buyer in India?
Quick answer
A first time home buyer in India is someone who has never owned residential property in their name anywhere in the country at the time of applying. For PMAY 2.0 subsidies, eligibility also demands that the applicant hasn't received housing finance assistance from the government since 1 October 2016.
The legal definition is strict. You qualify only if no residential property appears in your name across India at the moment of application. Even inherited flats count against you.
Selling a registered property five years ago also disqualifies you from scheme benefits. Private banks may still approve standard loans regardless.
Salaried and self-employed applicants face the same definition. The distinction only matters for government subsidies, where the government tracks PAN-linked ownership and past subsidy utilization. Always ask about first-time buyer concessions during the interview stage.
Phase 1: Financial Readiness and CIBIL Scores
Before you shortlist projects, lock down your finances. Banks evaluate your application long before they approve it. Small tweaks now can save you lakhs over the loan life.
Achieving the 750+ score target
A CIBIL score above 750 is the sweet spot. Scores in the 750–900 range give you access to the lowest tier interest rates and faster processing. A score between 700 and 750 may still get approved, but banks often add a spread to the base rate or cap the loan tenure.
If your score sits below 750, start cleaning it up three months before you apply. Pay all credit card bills on time and avoid new personal or auto loans that spike your debt-to-income ratio.
Length of credit history matters, so keep old cards open. Request a free annual credit report to spot errors. Correcting one misreported late payment or hard inquiry can jump your score quickly.
Calculating your true affordability and down payment
Banks typically fund 75% to 90% of the property value. You must arrange 10% to 25% in cash upfront for the down payment. That isn't your only cash requirement though.
You also need separate funds for stamp duty, registration, and the maintenance corpus. We break down those numbers in the next section.
Rule of thumb: Target having 25% to 30% of the listing price in liquid cash ready before you sign an agreement. This buffer covers the down payment and prevents the awkward situation of being forced to cancel after paying token amounts.
Here is a worked example showing the total cash needed for a mid-size property.
Understanding the Real Cost: Hidden Expenses Beyond the Listing Price
The listing price is never the final price. Every buyer in India faces additional costs at the time of booking and registration. These expenses usually add 8% to 12% to the flat's cost. Ignoring them is the single most common mistake new buyers make.
| Cost Component | Amount (₹) |
|---|---|
| Down Payment (10% of ₹60L) | 6,00,000 |
| Stamp Duty (approx 6%) | 3,60,000 |
| Registration Fee (approx 1%) | 60,000 |
| Maintenance Corpus (usually 2 years) | 60,000 |
| Brokerage / Legal / Processing | 90,000 |
| Total Additional Cash Required | ₹5,70,000 |
On a ₹60 lakh purchase, you would need roughly ₹6.57 lakh in hand to complete the transaction. This applies even if the bank sanctions a 90% loan. The brokerage line assumes you hire a channel partner for a resale transaction. Their common rate sits between 1% and 2%. For new flats purchased directly from builders, this charge disappears. Replacement costs like legal due diligence, technical verification, and document charging remain necessary.
Maintenance trap. Some buyers pay the maintenance corpus to the builder without checking the society bylaws. If the builder hands over control to a managing committee later, demand a reconciliation statement. Builders cannot retain excess maintenance fees beyond what is required for the specified period.
Stamp duty and registration rates vary by state. Women buyers often receive a concession in certain states, reducing stamp duty by up to 1% to 2%. Verify the latest IGR notification for your state, as these concessions occasionally expire or get modified.
Phase 2: Shopping for Home Loans (2026 Rates and Terms)
As of September 2026, home loan interest rates generally sit between 8.35% and 9.5% p.a. Female borrowers and premium salary accounts often see 0.05% to 0.10% lower rates. Tenure stretches up to age 65 or 70, whichever comes earlier for most lenders.
Comparing interest rates and lenders
Chasing the lowest headline rate misses the bigger picture. Two lenders offering 8.50% can end up costing different amounts. Processing fees, prepayment penalties, and turnaround times matter just as much. Focus on the total cost of the loan and the flexibility you might need later.
| Feature | SBI | HDFC Bank | LIC Housing Finance |
|---|---|---|---|
| Interest Rate Range | ~8.35% – 9.20% | ~8.45% – 9.50% | ~8.40% – 9.45% |
| Processing Fee Waiver | Often waived for employees | Frequent discounts on digital applications | Occasional promotional waivers |
| Prepayment Rule | Zero penalty on floating | Zero penalty on floating | Zero penalty on floating |
| Turnaround Time | 15 – 25 days | 10 – 20 days | 20 – 30 days |
All three major lenders currently charge zero penalty on prepayment for floating-rate loans, which is standard for public and private sector banks. The differences lie in processing fee structures and service speed.
SBI tends to have longer queues. HDFC moves faster for salaried professionals with existing relationships. LIC Housing Finance handles complex profiles competitively but processes documents slower.
Decoding LTV ratios, processing fees, and foreclosure rules
Loan-to-Value dictates how much the bank lends against the property valuation. For loans above ₹75 lakh, RBI caps funding at 80%. This forces you to arrange a larger down payment. Processing fees range from ₹5,000 to ₹20,000 plus GST. Negotiate these hard. Many branches waive them for high CIBIL scores or salary account holders.
Foreclosure rules allow you to close the loan early. With floating-rate loans, you can foreclose at any time without penalty under current regulations. Fixed-rate loans may carry foreclosure charges. If you expect a bonus hike or business growth that could let you clear the loan fast, confirm the foreclosure terms before signing.
Check your [home loan EMI calculator tool] to model EMIs across different tenures and rates. Small changes in tenure affect total interest significantly.
Extending tenure lowers the EMI but increases total interest paid over the life of the loan.
Leveraging Government Subsidies: PMAY 2.0 and PMAY-Gramin
The Pradhan Mantri Awas Yojana remains one of the strongest supports for a first time home buyer. PMAY 2.0, active through the Credit Linked Subsidy Scheme, offers direct interest subvention.
How the 4% Interest Subsidy works in practice
Under the interest subsidy component, the government credits 4% on the first ₹8 lakh of your home loan. This applies to eligible income brackets. For middle-income groups, the benefit reduces your effective interest rate significantly for the initial portion of the loan.
Worked example: Assume a home loan of ₹25 lakh for a ₹40 lakh property. The subsidy calculates strictly on the first ₹8 lakh.
At 4%, the government credits ₹32,000 directly to your account. Your principal balance instantly drops to ₹24.68 lakh, cutting your monthly EMI and total interest.
If your sanctioned loan is less than ₹8 lakh, the subsidy applies to the actual loan amount. For a ₹6 lakh loan, you would receive ₹24,000 as subsidy.
Rural buyers can look at PMAY-Gramin, which provides direct benefit transfer grants rather than interest subsidies. Current grant limits stand at ₹1.20 lakh for plains regions and ₹1.30 lakh for hilly and difficult areas. The grant amount depends on household size and category status. Verify eligibility on the official PMAY urban and rural portals, as beneficiary lists update periodically.
Phase 3: The Complete Purchase Timeline
The purchase journey breaks into distinct phases. Rushing through early steps causes delays and disputes later. Here is the operational sequence most first-time buyers follow.
- Pre-approval: Get sanction letter before visiting too many sites. Validity runs 3 to 6 months.
- Site visits and RERA check: Verify project registration on your state RERA portal. Check for occupancy certificate status and builder track record. Use our [RERA project verification tool] to cross-reference claims.
- Due diligence: Hire a property lawyer to verify title deeds, encumbrance certificates, and approved building plans. For resale, this step is non-negotiable.
- Agreement drafting and notarization: Review every clause. Pay attention to possession timelines, penalty clauses for delayed handover, and variation in carpet area calculations.
- Token payment and booking: Usually 0.5% to 1% of property value. Ensure the receipt clearly labels this as a token/booking amount and references the agreement draft.
- Home loan disbursement: Bank releases funds in tranches aligned with construction progress (for new projects) or fully at registration (for resale).
- Registration and stamp payment: Visit the sub-registrar office with both parties. Pay stamp duty either online or at the designated bank branch. Update the deed in your name.
- Possession and handover: Inspect the property for defects. Maintain a snag list. Pay remaining balances upon satisfactory handover.
- Khata / Mutation transfer: Apply for municipal khata transfer and utility connection updates. This can take weeks to months depending on local corporation efficiency.
- Insurance: Secure fire and hazard insurance for the structure. Lenders often require this before disbursing the full loan.
- Moving and governance setup: Join the resident welfare association or society. Understand the bye-laws before making alterations.
Each phase builds on the previous one. Skipping due diligence saves a few weeks but risks legal entanglements that last years.
Expect the timeline from application to possession on a new project to span 18 to 30 months.
| Check Point | What to Verify |
|---|---|
| Total interest cost | Ask for a statement showing total interest over full tenure at proposed rate. |
| Processing charges | Confirm exact fee + GST. Ask for waiver possibilities. |
| Documentation fees | Some lenders charge per-page fees or valuation fees not included in processing. |
| Rate stability period | How long does the announced rate hold during processing? Often 30 to 60 days. |
| Turnaround commitment | Ask for estimated days from application to disbursement for your profile. |
Final Checklist for First Time Home Buyers
Before you hand over the token amount or sign the sale deed, run through this decision rule. It separates prepared buyers from those who react to pressure sales tactics.
- Do you have 25% to 30% of the listing price in liquid cash?
- Has the property been verified by a lawyer and independent technical expert?
- Does the carpet area match the RERA-certified plan?
- Have you compared the total interest payable across two lenders, not just the EMI?
- Is the project RERA registered and is the OC or CC status clear?
- Have you checked your CIBIL score recently and resolved any errors?
If you answered yes to all six points, you are in a strong position. Pause the process if you did not. Address the gaps first.
No developer will delay possession indefinitely to accommodate a buyer who skips these steps.
Frequently asked questions
How much down payment do I need for my first house in India?
Most banks fund 75% to 90% of the property value, leaving you responsible for a down payment of 10% to 25%. If the loan exceeds ₹75 lakh, RBI guidelines cap funding at 80%, raising your cash requirement. On top of this, set aside an extra 15% to 20% in savings for stamp duty, registration, and other charges to avoid cash crunches during registration.
Can I get a home loan with a CIBIL score of 650?
Getting a loan with a 650 score is possible but difficult. Scores between 700 and 750 still face scrutiny, while below 700 leads to rejections or high spreads adding 1% or more to the interest rate. Banks view 650 as indicating repayment risk. Spend three months improving your score by clearing pending dues and avoiding new credit inquiries before applying.
Is PMAY 2.0 active in 2026 for first-time buyers?
Yes, the PMAY Credit Linked Subsidy Scheme remains active through 2026. It provides a 4% interest subsidy on the first ₹8 lakh of eligible home loans for qualifying income bands. You must not have owned any residential property previously, and the family income must fall within the MIG I or MIG II slabs defined by the Ministry of Housing. Subsidy is credited directly to the loan account upon disbursement.
What hidden costs are involved in registering a flat for the first time?
Beyond the listing price, expect to pay roughly 8% to 12% in additional expenses. Key costs include stamp duty (3% to 7% depending on state and gender concessions), registration fees around 1%, maintenance corpus deposits often requiring two years' worth, legal and technical verification fees, and brokerage charges of 1% to 2% if you use a channel partner for resale transactions.
When should I apply for PMAY-Gramin versus PMAY-Urban?
Choose PMAY-Gramin if your property falls under a rural locality listed on the official Census of India map. Rural beneficiaries receive direct benefit transfer grants of ₹1.20 lakh for plains and ₹1.30 lakh for hilly zones, which differ from the urban interest subsidy model. Urban PMAY focuses on CLSS interest credits. Apply based on location, not convenience, since reclassification can cause approval delays.
Sources
- HDFC Bank: Government Housing Schemes for First-Time Home Buyers: PMAY 2.0 and PMAY-Gramin eligibility details, grant amounts (accessed September 2026)
- DirectoHome: Home Loan Guide for First-Time Buyers India 2026: Current interest rates (8.35–9.5%), max loan tenure age (accessed September 2026)
- Square Yards: First-Time Home Buyer Guide India: LTV ratios, hidden cost percentages (8–12%), down payment rules (accessed September 2026)
- CreditSmart: First-Time Home Buyer Complete Guide India 2026: 11-phase timeline, pre-approval validity (accessed September 2026)
- Bajaj Finserv Markets: Home Buying Guide for First Time Home Buyers in India: Basic qualification criteria (accessed September 2026)
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.