New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
Services
FOR BUYERS & RENTERS
FOR REAL ESTATE DEVELOPERS

Refer other Connectors &
Multiply IncomeRefer other Connectors
& Multiply Income
Refer KuberX & earn
commission on every
loan they get
disbursed.


Scan & Download
©PropTech Pulse 2025, All rights reserved.


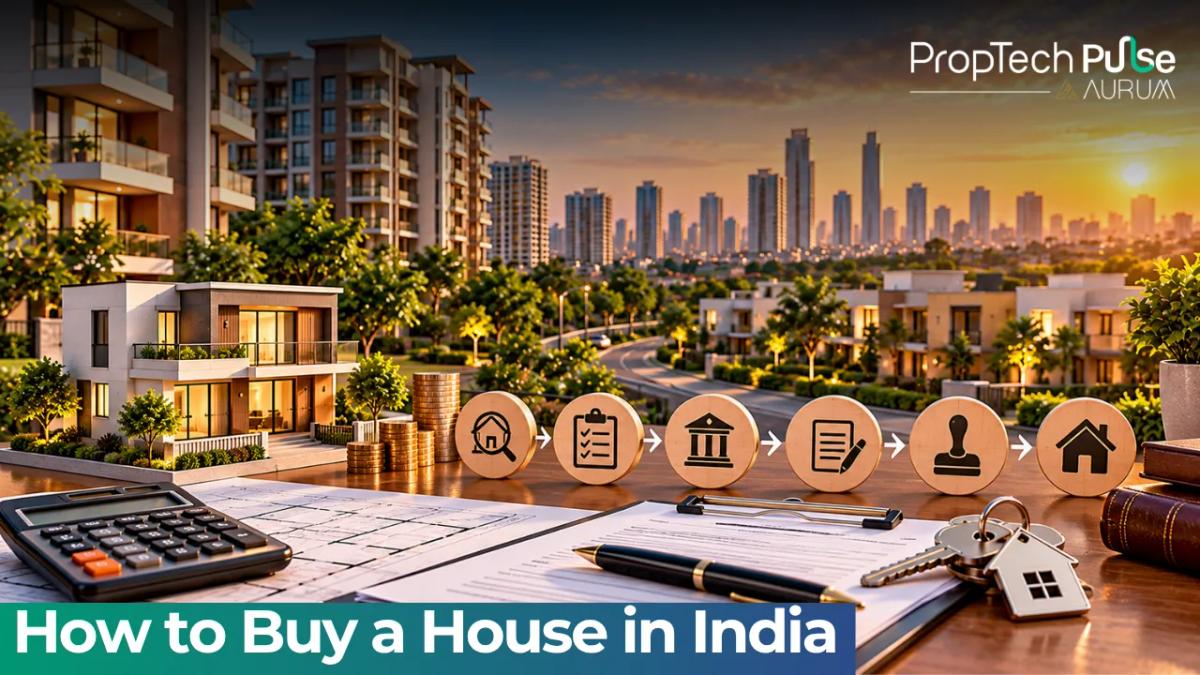
Figuring out how to buy a house safely starts long before you view a single flat. The path demands patience and strict document handling. Focus on the safeguards protecting your capital, starting with the hidden costs that trip up seasoned investors.
Assess your finances and set a realistic budget
Quick answer
This guide shows how to buy a house without wrecking monthly cash flow. Focus on actual spending power rather than listing prices. Banks cap loans at five times yearly net pay, so factor in stamp duty, registration, and GST before requesting pre-approval. Ignoring upfront costs strains finances rapidly.
Budgeting works backwards from the final price tag, not forwards from your salary. Many first-timers assume monthly installments handle everything. They don't. A ₹90 lakh flat demands liquid cash upfront for stamp duty, registration, GST, and legal checks before you pay the builder balance.
Factor in hidden costs
Competitors mention stamp duty but skip smaller line items adding thousands. Here is how upfront charges stack up across major cities as of September 2026:
| State / City | Stamp Duty (Men) | Stamp Duty (Women) | Registration Fee |
|---|---|---|---|
| Maharashtra (Mumbai & Pune) | 5% | 5% (concessions vary) | 1% |
| Delhi NCR | 6% | 4% | 1% |
| Tamil Nadu (Chennai) | 7% | 7% | 4% |
| Uttar Pradesh (Noida, Lucknow) | 7% | 6% | 1% |
| Karnataka (Bengaluru) | 5% | 5% | 1% |
| Telangana (Hyderabad) | 5% | 5% | 1% |
| Gujarat (Ahmedabad) | 6% | 6% | 1% |
| Rajasthan (Jaipur) | 7% | 7% | 1% |
| Average Additional Cost on ₹80 Lakh Flat | ₹4.8 lakh to ₹6.4 lakh + Registration | ||
GST applies strictly to under-construction projects while resale flats over five years escape this levy. Affordable units attract five percent rates, and luxury properties face twelve percent. Reserve extra funds for municipal taxes sellers shift to you before handing over keys.
Cash buffer rule Never sign an Agreement to Sell if your liquid savings drop below twelve percent of the property value. That reserve covers legal checks, unexpected maintenance calls, and initial furnishing without forcing you into high-interest personal loans.
Compare home loan offers and understand eligibility
Rates typically sit between 7.15% and 8.75%, shifting based on your credit score and employer type. Banks weigh the Debt-to-Income ratio alongside the Fixed Obligations to Income Ratio (FOIR). Your total monthly outflow must stay capped at fifty-five percent of gross income.
Pull a CIBIL score above 750 to secure the lowest slabs and quicker payouts. Scores between 650 and 749 trigger higher rates or bigger down-payment requests. Demand an Estimate of Remaining Charges (ERC) sheet beforehand. It exposes hidden processing fees, penalty clauses, and tenure tweaks that banks hide in the fine print.
Shortlist properties and inspect the location
Scrutinize locations with healthy skepticism. Livability dictates exit strategy. Proposed transit lines sound great until construction stalls for years. Target zones with functioning amenities today instead of relying on five-year masterplans.
What to check during a site visit
Builders dress model units with high-end finishes and spacious layouts. Those setups conceal structural flaws. Walk through your chosen apartment during a downpour and spot these red flags:
- Water logging or damp patches on ground-floor plinths or terrace edges.
- Weak natural light in the living room or bedrooms during midday (indicates poor ventilation).
- Excessive street noise bleeding through walls (ask to open windows facing the road).
- Uneven flooring tiles or mismatched grout lines (suggests rushed finishing).
Measure carpet area against the brochure figures immediately. Carpet area captures usable inner space plus internal wall thickness. Super built-up area inflates the number by adding common zone shares like lobbies and stairs. RERA mandates sales based strictly on carpet area, meaning discrepancies exceeding four percent justify renegotiation.
Verify the legal compliance and RERA registration
[INTERNAL LINK: How to check if a builder is RERA registered]
Verify compliance beyond standard paperwork. Your RERA registration number functions as a primary shield. Marketing projects or collecting advances without it remains illegal.
Enter the project code into the state portal beforehand. Review launch dates and disciplinary histories. Cross-check approved blueprints against rising structures. Unauthorized floor additions instantly invalidate your insurance coverage.
Finalise the deal and secure the agreement
The Agreement to Sell sparks most ownership disputes. This document fixes final pricing, payment calendars, and deadlines. Demand milestone-linked disbursements for new builds.
Tie funds to physical benchmarks like foundation pouring or slab casting. Work halts automatically freeze your payment liability. Audit penalty clauses meticulously. Developer possession delays must attract your home loan interest rate.
Drafts routinely punish buyers while excusing builder delays. Write every verbal commitment about parks and clubhouses directly into the annexure. Verbal assurances carry zero legal weight.
Register the property and update records
Settle all outstanding dues and collect possession papers before visiting the Sub-Registrar. Bring fresh ID proofs, passport photos, the draft deed, the occupancy certificate, and paid challans. Staff will scan fingerprints and take photos to prevent proxy registrations.
Pay stamp duty and registration fees via state portals before submitting the deed. The registrar returns your stamped document within forty-eight hours. Mutation updates land revenue records to reflect your name legally. Unupdated titles keep tax bills flowing to the former owner, creating severe liability gaps during emergencies.
Summary: Your home-buying checklist
Treat purchases as risk management. Verify paper trails before transferring funds. Track mutation updates strictly. Follow these steps and ownership transfers smoothly.
Frequently asked questions
What documents are required to buy a house in India?
You need the title deed proving clean ownership history, an Encumbrance Certificate confirming zero outstanding loans, the approved building layout plan, and the Completion or Occupancy Certificate. Salaried applicants must supply Form 16, bank statements for the last six months, and latest IT returns. Buyers purchasing off-plan under-construction projects also require the builder's RERA certificate and the executed Agreement to Sell drafted by an independent property lawyer.
How can I calculate my home loan eligibility?
Lenders multiply your monthly gross salary by a standard multiplier, often twenty times, then subtract existing monthly debt obligations like credit card minimums or vehicle EMIs. The resulting net figure forms your Maximum EMI capacity. Ensure your total fixed commitments stay below fifty-five percent of your income, because banks reject applications that exceed this FOIR threshold during final underwriting checks.
What is the difference between carpet area and super built-up area?
Carpet area measures the exact usable square footage inside your apartment walls, including internal partition thickness. Super built-up area adds a proportional share of common zones such as elevators, stairs, gardens, and clubhouses. Under current RERA guidelines, developers must quote prices based solely on carpet area, making it the only metric that reflects genuine value for money.
Is RERA registration mandatory for builders?
Yes. Any residential project exceeding eight hundred square metres or containing more than eight apartments must register on your state Real Estate Regulatory Authority portal before marketing or collecting advances. Unregistered builders face heavy fines, project halt orders, and inability to lock in buyer payments through escrow accounts, leaving purchasers legally unprotected during construction delays.
How long does the property registration process take?
Physical presence at the Sub-Registrar office takes roughly three to four hours to complete biometric scans, document verification, and digital stamp affixing. Official document processing typically returns within forty-eight working days. Mutation of municipal land records follows separately and can take anywhere from thirty to ninety days depending on local administrative workloads and pending property tax clearance.
Sources
- Aditya Birla Capital: State-wise stamp duty and registration fee tables (accessed September 2026)
- Visheshank: GST slabs, home loan interest ranges, and credit score thresholds (accessed September 2026)
- LT Finance: 2026 home buying process framework (accessed September 2026)
- PropertyPistol: Foundational steps and prerequisite overview (accessed September 2026)
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.