New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
©PropTech Pulse 2025, All rights reserved.


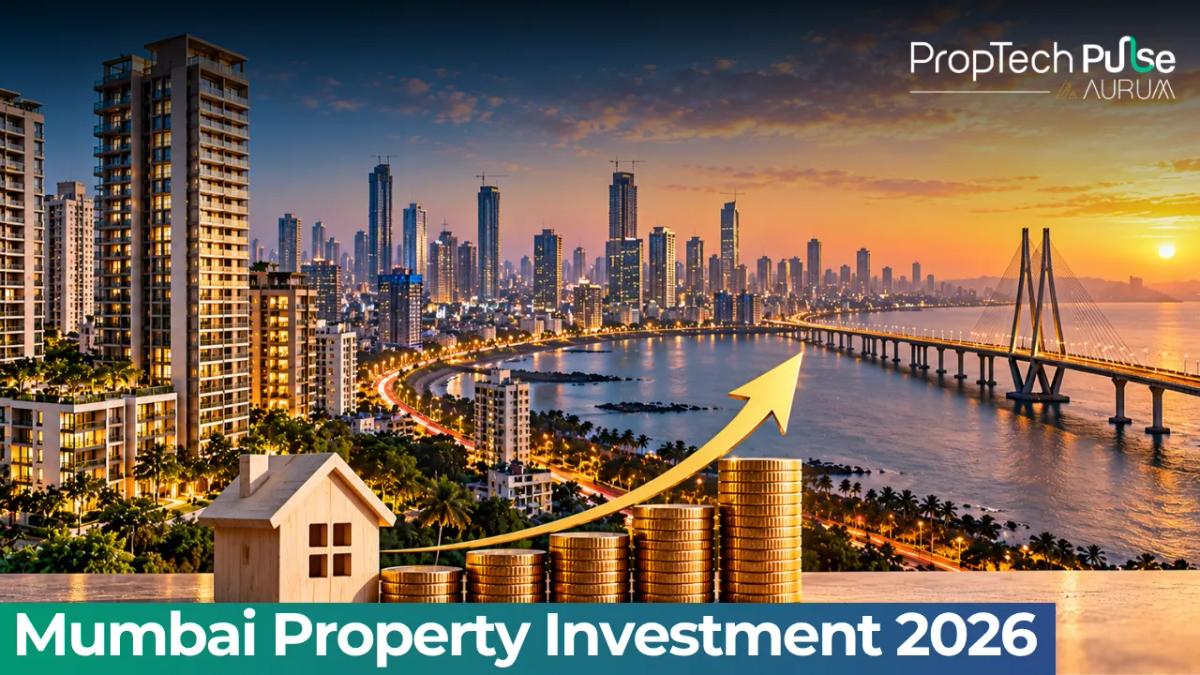
If you have been tracking property investment in Mumbai from the sidelines, 2026 feels less like a gamble and more like a timed opportunity.
Metro Line 3 is now running. The Atal Setu has slashed commute times across the western suburbs. Meanwhile, NMIA is pulling in commercial tenants faster than construction crews can finish buildings.
The market is shifting away from hype. Hard supply constraints and heavy infrastructure spending now dictate pricing. An NRI parking foreign capital here sees purchasing power jump roughly 15–20% versus 2021. Domestic salaried buyers are currently securing home loans from 7.25%, following the RBI's decision to hold the repo rate steady at 5.25% in April 2026.
Forget generic city comparisons. This guide focuses strictly on closing costs, current gross yields, and the actual math behind buying in Powai versus Panvel. Securing a flat requires keeping a 10–12% cash buffer above the headline price. Protect your liquidity by understanding exactly how those extra lakhs add up.
The state of property investment in Mumbai in 2026
Quick answer
Property investment in Mumbai remains highly viable in 2026. The completion of Metro Line 3, the Coastal Road, and NMIA has fundamentally reduced commute times. Simultaneously, land scarcity keeps long-term appreciation ahead of the national average. Buyers should budget for 7.25–8.70% home loan rates, expect 3–5% residential gross yields, and keep a 10–12% cash buffer above the base price to cover stamp duty, registration, and society deposits.
Delivery has replaced growth. Over the last decade, Mumbai wrestled with stalled projects and uncertain possession dates. Today, MahaRERA's escrow mandate forces builder collections into dedicated construction accounts instead of corporate debt. That structural shift alone improves floor space index realisation and cuts delayed handover probabilities.
Connectivity shifts act as the second lever. Purchasing land in the Navi Mumbai belt or northern suburbs means pricing in future commute times. Active metro lines will eventually shrink travel windows to single-digit minutes. The coastal road currently converts a chaotic two-hour drive into a steady forty-minute run. Early buyers positioned near station clusters and airport corridors have already secured solid gains.
Speculation drives fewer deals now. Multinationals flocking to South Mumbai and BKC have kept the corporate rental market extremely active. Your task is simply choosing a lane: monthly rent, long-term capital gains, or legacy wealth preservation. Each objective demands a distinct entry strategy.
The real cost ladder: budgeting beyond the base price
Most investors look at the carpet area price quoted in brochures and assume that is their total outlay. It is not. In Mumbai, the gap between the brochure figure and the money leaving your account averages 10–12%. Missing this buffer is why some deals force residents to stretch their EMI budgets to uncomfortable levels.
Stamp duty and registration in Maharashtra form the largest upfront chunk. You need to build in the standard rate to avoid underestimating your closing costs, even with concessions for women or first-time buyers. Add integrated GST for under-construction units. Factor in brokerage if you use a channel partner, plus mandatory club membership or parking charges. New residents also face upfront society charges. Entrance fees and prepaid maintenance typically cover six to twelve months before you even unpack your boxes.
| Cost Component | Approximate % of Base Price | Rough Amount (₹) |
|---|---|---|
| Stamp Duty & Registration | 5.5% – 7% | 11,00,000 – 14,00,000 |
| GST (Under-construction) | 5% | 10,00,000 |
| Parking / Club Membership | 2% – 3% | 4,00,000 – 6,00,000 |
| Brokerage (if applicable) | 1% – 2% + GST | 2,00,000 – 4,00,000 |
| Total Cash Buffer Needed | ~10–12% | ₹27,00,000 – ₹34,00,000 |
Keep that buffer separate from your down payment. If your goal is a ₹2 crore apartment, your liquid savings should comfortably cover ₹2.2 to ₹2.25 crore so that you aren't borrowing for closing costs or stripping emergency funds to pay society entrance fees.
Micro-market map: where to buy for appreciation vs yield
Mumbai is not one market. It is a collection of distinct suburbs operating on different pricing and demand cycles. Treating Thane the same way as Lower Parel is why many portfolios miss their targets. You have to pick a lane.
For capital appreciation: Look at the C-line, Lower Parel, and Andheri West. These areas hold value because employment hubs anchor them. South Mumbai and Bandra West capture around 60% of high-value transactions above ₹5 crore, heavily favoured by NRI capital seeking legacy assets. If your horizon is seven-plus years and you want safety first, these pockets offer steady growth with lower volatility. They do not offer quick flips; the law of large numbers applies here.
For rental yields: Powai, Goregaon, and parts of Thane perform best. Powai attracts IT employees and corporate expats willing to pay premium rents for proximity to office parks. Goregaon benefits from the upcoming film city expansion and established connectivity. Sectors along the Trans-Harbour line sit at roughly ₹13,100 per sq ft right now. This accessibility appeals to investors targeting young professionals who need relative affordability.
Lifestyle and legacy assets: Mahalaxmi, Malabar Hill, and Juhu operate on a different scale entirely. Here, you are buying scarcity. Land parcels barely exist, which means supply cannot flood the market when demand dips. These are generational holds rather than tactical plays.
| Target Goal | Area Focus | Why It Works Now | Expected Gross Yield |
|---|---|---|---|
| Capital Appreciation | Worli, Lower Parel, Andheri West | Direct access to BKC and SEEPZ employment corridors; high-end tenant pool | 2–3% (Residential), 4–6% (Commercial) |
| Rental Yield | Powai, Goregaon, Thane, Navi Mumbai | Corporate hiring spikes and metro connectivity draw consistent working professionals | 3–4% (Residential), 5–7% (Commercial) |
| Legacy Wealth | Bandra, Juhu, Mahalaxmi | Absolute land scarcity prevents oversupply; high NRI demand floor | 1.5–2.5% (Residential) |
Read our breakdown on [What Is Rental Yield in India? Calculate It Right (2026 Guide)](https://www.aurumproptech.in/pulse/blog/what-is-rental-yield-india) to understand how gross yields translate into actual pocket money once you factor in vacancy periods, property management, and service tax.
Running the numbers: yields and home loans at 5.25% repo
Momentum doesn't pay your EMI. Cash flow does. The RBI held its repo rate at 5.25% during the April 2026 monetary policy committee meeting, and lenders have passed those cuts through to consumers. Home loan rates now sit between 7.25% and 8.70%, depending on whether you are salaried or self-employed and which lender you approach.
If you are financing a portion of your purchase, apply the standard affordability check before signing anything. Your monthly EMI should not exceed 35–40% of your gross monthly income. A common mistake is calculating eligibility based on a 30-year tenure at optimistic interest rates. You quickly realize your disposable income vanishes when inflation hits maintenance charges or unexpected repairs appear.
Take a hypothetical scenario: a household with a combined monthly income of ₹2,50,000. Strictly applying the 40% buffer, your maximum comfortable EMI lands around ₹1,00,000. At roughly 8.0% interest over a 20-year tenure, that qualifies you for a loan principal near ₹1.1 to ₹1.15 crore. Factoring in a 20% down payment requirement, your effective buying power sits safely between ₹1.35 and ₹1.45 crore. Anything pushing beyond that puts stress on your finances.
Vacancy reality check A 3–4% gross rental yield sounds attractive until you account for vacant months. Always run your proforma assuming 10–15% annual vacancy, especially in suburban areas where tenant turnover moves slower than in prime central belts.
When you compare residential returns to commercial opportunities, remember the risk profiles differ. Residential demands higher capital but offers lower vacancy risk and stronger regulatory protections. Commercial spaces promise double-digit gross yields but come with longer lock-in periods and stricter lease structures. Compare the cash flow models and regulatory hurdles side-by-side in our guide on [Commercial vs Residential Property India: Yields & Risks](https://www.aurumproptech.in/pulse/blog/commercial-vs-residential-investment-india-2026) to weigh how each asset class fits your liquidity needs.
NRI buying rules and FEMA compliance
NRI capital continues to flow heavily into Mumbai. During FY2025, NRI purchase volume crossed ₹18,000 crore, representing a 22% year-on-year increase. This volume concentrates heavily in Worli, Bandra West, and Lower Parel, where premium inventory meets diaspora demand for secure domestic assets.
Foreign nationals of Indian origin can buy residential or commercial property in India using permissible remittances from their Non-Resident External (NRE) or Non-Resident Ordinary (NRO) accounts. You cannot use foreign currency remitted under the Liberalised Remittance Scheme (LRS) for purchasing real estate unless the specific scheme permits it, so stick to NRE/NRO channels for clarity. There is no upper limit on the number of properties an NRI can acquire. However, you must adhere to strict repatriation rules if you wish to convert sales proceeds back to foreign currency later.
Taxation matters. If you sell the property within five years of acquisition, it attracts short-term capital gains taxed at your slab rate. Holding it longer qualifies for long-term capital gains at 12.5% (after March 2024 budget changes), provided Securities Transaction Tax is not applicable. You must also deduct TDS at the prescribed rate during sale and report it via Form 26QB. Keeping accurate records of exchange rates at the time of purchase is essential for future calculations.
The pre-signing due diligence checklist
Mumbai's market has matured under MahaRERA regulations. That does not mean you sign the agreement without verifying everything yourself. Builders still attempt to hide encumbrances in multi-layered titles, and older buildings carry baggage that new purchases do not face.
- Title chain verification: Engage a property lawyer to trace ownership back at least three generations. Confirm there are no litigated plots or pending succession certificate issues.
- MahaRERA escrow status: Legitimate developers must deposit 70% of buyer payments into an escrow account designated solely for that project. Ask for the project's RERA number and validate it on [the official MahaRERA portal](https://maharera.maharashtra.gov.in).
- OC and CC clearance: For resale flats, confirm the Occupancy Certificate and Completion Certificate are physically issued. Do not rely on builders claiming these documents are merely "in process". Buildings without these cannot legally be handed over keys, and societies struggle to get utility transfers.
- Builder reputation check: Research the developer's track record for timely delivery. Look at completed projects, not just marketing renderings. Check consumer court complaints from the last five years.
[INTERNAL LINK: How to verify MahaRERA project status]
Your next step before committing capital
If your primary goal is capital preservation alongside moderate growth, target the established southern and central belts where employment anchors keep vacancies low. Need immediate rental income to service an EMI instead? Aim toward the northern suburbs and Thane, where young professionals cluster around new tech parks and metro lines. Never stretch your liquidity below the 10–12% buffer for closing costs, and treat every gross yield number with a 15% vacancy discount baked in.
Fundamentals supporting Mumbai's real estate economy are stronger now than they have been in half a decade. Infrastructure execution has moved past promises, and lending rates have cooled enough to improve affordability margins. Run the numbers for your specific situation, validate the paperwork thoroughly, and commit only the capital you can afford to lock for a minimum of five years.
Frequently asked questions
Is property a good investment in Mumbai in 2026?
Yes, property investment in Mumbai carries strong fundamentals right now. The completion of critical infrastructure like Metro Line 3, the Atal Setu coastal road, and the Navi Mumbai International Airport has structurally altered commute times and boosted demand in previously disconnected suburbs. Combined with sustained NRI capital inflows hitting ₹18,000 crore last fiscal year, liquidity remains healthy across multiple price segments.
What is the minimum amount needed to invest in property in Mumbai?
Entry-level new launches in outer suburbs like Navi Mumbai, Thane, and Dombivli start around ₹40 to 50 lakh for compact 1-BHK configurations. However, you must add at least 10–12% of the base price to cover stamp duty, GST, brokerage, and society deposits. Therefore, maintaining liquid funds of roughly ₹50 lakh to ₹55 lakh provides a realistic entry point for most first-time investors without stretching financing to risky levels.
Which area in Mumbai gives highest rental yield?
Areas adjacent to major employment hubs consistently deliver the strongest rentals. Powai leads for mid-to-high range 2 and 3-bedroom apartments, attracting IT professionals who prefer proximity to office parks. Suburbs along the Thane-Belapur corridor and the upcoming Trans-Harbour Line stations also perform well, offering yields closer to 4% when accounting for vacancy. Prime southern areas rarely exceed 2% gross yields despite commanding premium absolute rents.
Can NRI buy property in Mumbai without visiting India?
Yes, Non-Resident Indians can purchase residential or commercial property in Mumbai completely remotely. You simply need to appoint a legally authorized Power of Attorney resident in India to execute the sale deed and handle document submission at the sub-registrar office. The transaction funds must originate from your NRE or NRO bank account in India, and the property registration can be processed electronically through Maharashtra's e-registration portals.
What are the hidden costs when buying property in Mumbai?
Beyond the carpet price, you will face stamp duty and registration charges averaging 5.5–7%, plus 5% GST on under-construction inventory. Builders almost always charge separately for parking slots, club memberships, and interior upgrades, which can easily run ₹5 to 8 lakh on top. Additionally, new society members pay an entrance fee and must prepay six to twelve months of maintenance charges before moving in.
Sources
- Property Butler: NRI purchase volumes, home loan rates, and NRI zone transaction data (accessed September 2026)
- Just Imagine Realty: EMI to income ratio guidelines and outflow buffer rules (accessed September 2026)
- Riyasat Infra: Panvel pricing averages and Navi Mumbai development catalysts (accessed September 2026)
- Keystone Real Estate Advisory: Macro trends regarding land scarcity and infrastructure shifts (accessed September 2026)
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.