New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
Services
FOR BUYERS & RENTERS
FOR REAL ESTATE DEVELOPERS

Refer other Connectors &
Multiply IncomeRefer other Connectors
& Multiply Income
Refer KuberX & earn
commission on every
loan they get
disbursed.


Scan & Download
©PropTech Pulse 2025, All rights reserved.


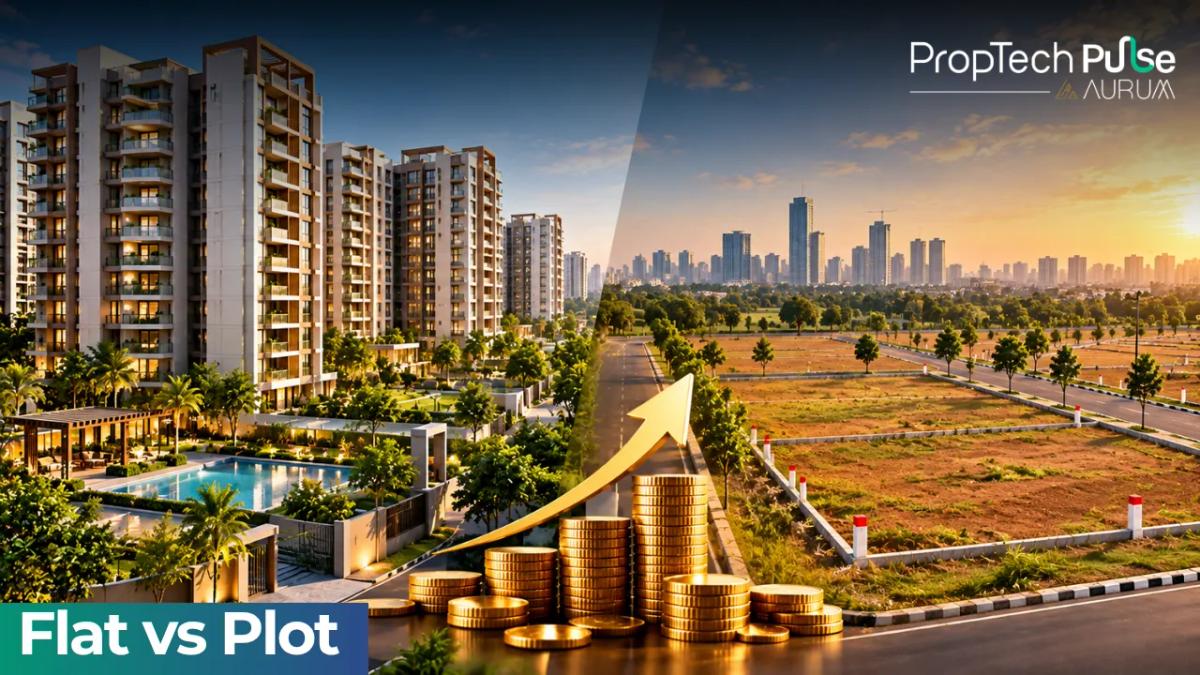
When deciding between flat vs plot, the short answer depends on your need for daily cash flow versus future wealth parking. If you want immediate rental income or a ready roof over your head, a flat wins. If you hold spare capital and can wait seven to ten years for appreciation, a plot pays off.
The return math: why higher appreciation isn't always better
Quick answer
Flats deliver 2% to 4% annual rental yield plus steady 4% to 7% price growth. Plots offer higher 8% to 15% appreciation but zero rental income. Your choice hinges on monthly cash flow versus long-term wealth parking.
Urban plots in growth corridors have historically delivered higher CAGR than residential flats. Research across major Indian metros pegs average flat appreciation between 4% and 7% annually. Land prices in well-planned zones frequently push past that range, hitting 8% to 15% yearly.
This looks compelling until you subtract the silent drains. An under-construction flat depreciates physically the moment you buy it, just like any consumer durable. You must factor that depreciation drag against the base appreciation. A vacant plot generates zero income. It sits there, demanding upkeep while its value remains theoretical.
Run the numbers over a seven-year holding period.
A ₹50 lakh flat appreciating at 6% compounds to roughly ₹74 lakh. Physical wear, brokerage, and shared corridor space trim the handover value closer to ₹71 lakh. Cumulative rental yield of 3% offsets some holding costs. A ₹50 lakh plot growing at 12% compounds to about ₹98 lakh after seven years.
It sounds superior, but only if you absorbed the entire cost of land taxes, fencing, and EMI without dipping into other savings. Strip away those holding costs, and the net surplus shrinks significantly. When weighing flat vs plot, always calculate the real exit value after every deduction.
The financing reality: EMI traps and loan parameters
Indian banks treat bricks and land differently when sizing a loan. For a residential flat, lenders typically offer 80% loan-to-value (LTV) at 8.5% to 9.0% interest, with tenures stretching to 30 years. A plot loan caps at 70% LTV, runs at 9.0% to 10.0%, and rarely exceeds 20 years.
The shorter tenure on a plot loan crushes your monthly cash flow. Consider two buyers injecting ₹50 lakh.
Buyer A targets a ₹50 lakh flat. The bank funds ₹40 lakh. At 8.75% over 30 years, the EMI lands near ₹31,000. A standard 3% gross rental yield nets ₹12,500 monthly. Half the EMI disappears automatically.
Buyer B buys the identical plot. The bank advances ₹35 lakh at 9.5%. The EMI jumps to roughly ₹35,400 for twenty years. Zero rental income cushions the blow.
That financing gap dictates survival. Cash flow beats paper gains when EMIs eat into other savings during the build phase. Premature exits become common. Gains get capped before the market peaks.
Hidden holding costs and legal exposure
Ownership carries recurring bills regardless of occupancy. A society maintains a roster of expenses: sinking funds, water and electricity maintenance, and security salaries. These run 0.1% to 0.15% of the property value every month. You also add 5% GST when buying under-construction, though rent receipts or resale premiums usually offset it later.
Plots present a quieter, yet equally persistent, cost structure. Municipal taxes rise annually based on road width and location assessments. Add fencing, a gate, and a caretaker salary. A ₹50 lakh plot runs you ₹5,000 to ₹8,000 monthly in upkeep before you lay a single brick.
Key takeaway: Infrastructure promises drive land prices, but ground work takes longer. Never buy land expecting the metro line or airport upgrade to arrive faster than the government's official tender schedule indicates.
The bigger risk sits in documentation. An under-construction flat falls under RERA guidelines, mandating progress-linked escrow accounts and protecting against delays. Land transactions lack this shield. You must verify the title chain, clear encumbrances, secure layout approval, and pull Non-Agricultural (NA) conversion orders.
Delays in NA conversion or zoning changes can stall your exit plan for years. Navigating flat vs plot legal exposure requires knowing where the regulatory safety net actually exists.
Performance by city: where land outpaces apartments
National averages obscure micro-market realities. A plot near a new metro line appreciates faster than a flat in a mature neighbourhood. Conversely, a built apartment block in a central business district holds value far better than raw land waiting for infrastructure.
| City zone | Avg. flat CAGR | Avg. plot CAGR | Infrastructure trigger |
|---|---|---|---|
| Bengaluru (North / ORR) | 5–7% | 10–14% | Airport expansion, Metro Line 2A |
| NCR (Noida / Jewar) | 6–8% | 12–16% | New Delhi airport completion, peripheral expressway |
| Hyderabad (Shamshabad) | 5–6% | 9–12% | Rail corridor upgrades, tech park extensions |
| Pune (Hinjjewadi / Wakad) | 6–7% | 8–10% | Metro Line 3 extension, IT SEZ growth |
Land delivers wider spreads in nodes like Devanahalli and Jewar.
Those gains arrive late. Announcements take years to become actual connectivity. If you cannot hold through gap years, theoretical appreciation never reaches your pocket.
Pick the asset matching your liquidity horizon. Paper promises require deep pockets.
Decision matrix: which should you pick?
Forcing a binary choice serves no one. Pick the asset matching your liquidity horizon and tolerance for legal paperwork.
- Choose a flat when you need monthly rental coverage, want the stability of a constructed building, require RERA-backed project oversight, or plan to occupy the unit within three to five years.
- Choose a plot when you already own other income-generating assets, have substantial liquid capital to absorb the initial LTV shortfall, and want to monitor the site yourself during construction delays or NA conversion processes.
Relying on a single salaried income? Lean toward a flat for predictable outflows. Running a business with variable cash flows? A tracked plot offers better long-term wealth preservation. The flat vs plot verdict rests entirely on your risk appetite.
Frequently asked questions
Is buying a plot better than a flat in 2026?
Depends entirely on your timeline. A flat provides immediate utility and rental yield if you move in or lease it out. A plot relies on future appreciation, meaning you must hold the land without income for seven to ten years while paying municipal taxes and EMI. If you need current cash flow or a ready-to-move structure, a flat suits the 2026 market better. If you have idle capital and can wait out infrastructure delays, land outperforms apartments over the long term.
Do plots appreciate faster than flats in India?
Historically yes, particularly in emerging suburbs near new highway interchanges or airport perimeters. Urban plots have shown 8% to 15% compound annual growth rates compared with 4% to 7% for constructed flats. However, land appreciation is lumpy. Prices sit stagnant for years while waiting for zoning approvals or sewer network connections, then spike abruptly when infrastructure completes. Apartment values trend smoother because built structures provide consistent utility regardless of nearby civic improvements.
Can I get a home loan for a plot?
Banks classify this differently. You can secure financing, but it is labelled a plot loan rather than a traditional home loan. Most lenders fund up to 70% of the assessed value at rates between 9.0% and 10.0%, capped at twenty-year tenures. Residential flat loans typically offer 80% funding at 8.5% to 9.0% over thirty years. Because the plot loan requires more upfront equity and carries a higher monthly repayment burden, you must ensure you retain enough liquidity to cover holding costs during the construction phase.
What are the hidden costs of buying a plot vs a flat?
A flat demands GST on the construction component, plus monthly society maintenance covering water, electricity, security staff, and elevator repairs. Plot ownership carries its own quiet drains. You face rising municipal property taxes, fencing expenses, a permanent gate, and a caretaker wage to prevent squatting or illegal dumping. Crucially, you absorb the entire financial liability for NA conversion fees, layout sanction lawyer charges, and potential litigation over title defects. These administrative costs rarely appear in the brochure.
Which gives better returns: apartment or land in Bangalore, Mumbai, or Pune?
Land outpaces apartments in high-growth corridors outside city centres. In Bengaluru, Devanahalli and areas along the Outer Ring Road show stronger land appreciation due to airport expansion. Pune's Hinjewadi fringe and Noida's Jewar belt deliver steeper land curves tied to metro lines and peripheral expressways. Older, fully developed suburbs in Mumbai and South Bangalore see tighter spreads, making existing apartments the safer bet. Always cross-reference the projected arrival date of the promised infrastructure; the investment fails if the timeline drags beyond your holding capacity.
Sources
- RupayWise Economic Analysis: CAGR ranges, rental yields, and loan EMI calculations for flats versus plots (accessed September 2026)
- The Economic Times: Bengaluru investor discussion on immediate rental income versus long-term land returns (accessed September 2026)
- State Real Estate Regulatory Authorities (RERA): Escrow account norms and delay penalties for under-construction projects (accessed September 2026)
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.
Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.