New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
Services
FOR BUYERS & RENTERS
FOR REAL ESTATE DEVELOPERS

Refer other Connectors &
Multiply IncomeRefer other Connectors
& Multiply Income
Refer KuberX & earn
commission on every
loan they get
disbursed.


Scan & Download
©PropTech Pulse 2025, All rights reserved.


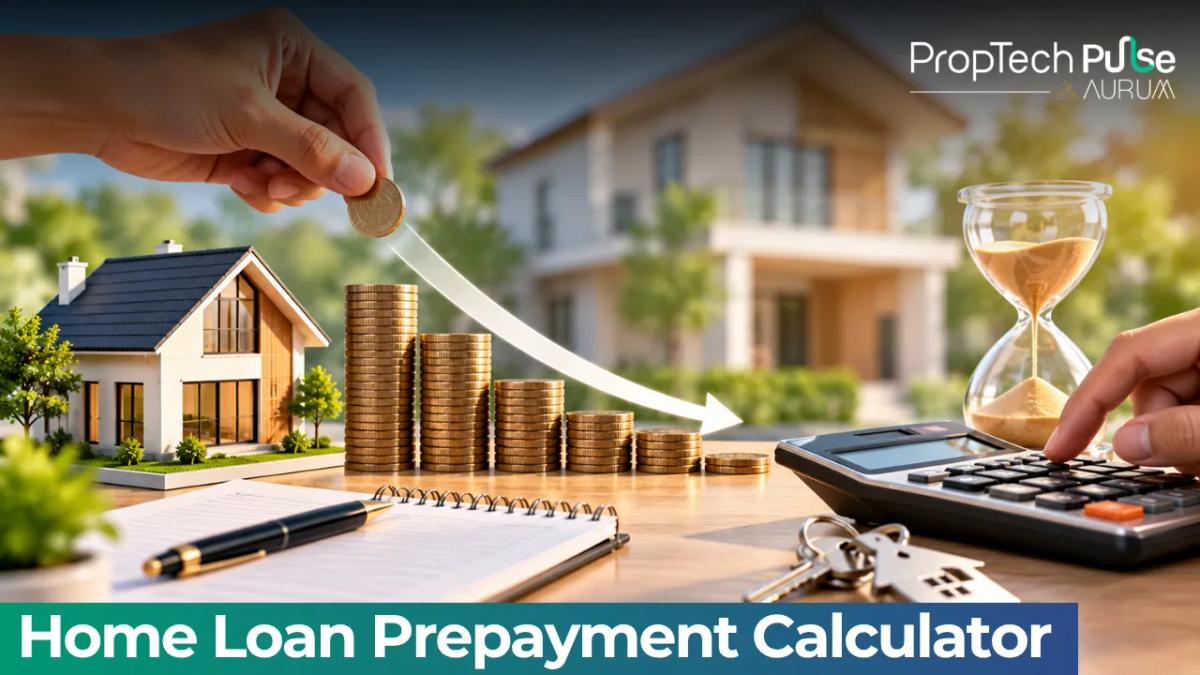
Pay ₹5 lakh extra on a ₹50 lakh home loan in the first year and keep the EMI unchanged: the loan ends four years early and you save about ₹16 lakh in interest. Pay the same ₹5 lakh in year ten and the saving drops to about ₹5.7 lakh. Timing matters more than the amount.
A home loan prepayment calculator shows you these numbers before you commit the money. Below: how the calculation works, what each type of prepayment does on a real loan, and what to check before you pay a rupee extra.
What a home loan prepayment calculator shows
Quick answer
A home loan prepayment calculator takes your outstanding balance, interest rate, remaining tenure and the extra amount you plan to pay. It then shows the new tenure or EMI, the interest you save, and the month your loan ends. Prepaying early and keeping the EMI unchanged saves the most.
Every part payment goes straight to the principal, so the interest for later months is calculated on a smaller balance. That is the whole mechanism. The calculator just repeats it month by month for the rest of the loan.
Start with your current EMI in the home loan EMI calculator (or a lender's own, such as the SBI home loan EMI calculator), then apply the prepayment logic below. Every figure in this guide uses one loan so the effects can be compared: ₹50 lakh at 8.5% for 20 years, with an EMI of ₹43,391. The rate is illustrative.
How the calculation works
First, find the balance you still owe. After each EMI, interest for the month is charged on the balance, and the rest of the EMI reduces it. Repeat that 12, 60 or 120 times.
| After | Balance still owed | Principal repaid so far |
|---|---|---|
| 1 year | ₹49.00 lakh | ₹1.00 lakh |
| 5 years | ₹44.06 lakh | ₹5.94 lakh |
| 10 years | ₹35.00 lakh | ₹15.00 lakh |
Source: author's calculation using the reducing-balance method. Your lender's statement will show your exact figure.
Second, subtract your part payment from that balance. Third, either keep the EMI and see how many months the new balance needs, or recompute a lower EMI over the original remaining months. The calculator does both. The mathematics of the first option is n = −ln(1 − B × i ÷ EMI) ÷ ln(1 + i), where B is the new balance and i is the monthly rate, but you don't need to work it by hand.
Lump sum: shorter tenure or lower EMI?
Assume you prepay ₹5 lakh after the first year. You have two choices.
| Option | New EMI | Loan ends after | Interest saved |
|---|---|---|---|
| Keep the EMI, shorten the tenure | ₹43,391 | 16 years (192 months) | ₹16.04 lakh |
| Lower the EMI, keep the tenure | ₹38,964 | 20 years (240 months) | ₹5.09 lakh |
Source: author's calculation. Interest saved is measured against the original loan with no prepayment.
Keeping the EMI gives more than three times the saving. Lowering the EMI feels comfortable, but it leaves the loan running the full term. If your budget can carry the old EMI, keep it. The guide to reducing home loan tenure explains how to tell the bank which option you want. If cash flow is tight instead, see these ways to reduce your EMI burden.
Why timing changes the saving
Interest is heaviest in the early years, so the same rupee saves more when it goes in early. Here is the same ₹5 lakh paid at three points, keeping the EMI unchanged.
| Paid after | Months saved | Interest saved |
|---|---|---|
| 1 year | 48 months | ₹16.04 lakh |
| 5 years | 36 months | ₹10.69 lakh |
| 10 years | 24 months | ₹5.71 lakh |
Source: author's calculation on a ₹50 lakh, 8.5%, 20-year loan. Rates are illustrative.
If you're going to prepay, do it soon. Waiting ten years to make the same payment cuts the saving by about two thirds. That is a strong argument for using bonuses and windfalls on the loan early rather than late.
Small monthly extras
You don't need a windfall. A steady top-up from the start does the work too.
| Extra per month | Loan ends after | Interest saved |
|---|---|---|
| ₹2,000 | 17 years 11 months | ₹6.69 lakh |
| ₹5,000 | 15 years 7 months | ₹13.89 lakh |
| ₹10,000 | 12 years 11 months | ₹21.79 lakh |
Source: author's calculation. Set a standing instruction with your lender so the extra goes to the loan account and doesn't just sit in your savings.
Before you prepay
- Check for charges. Floating-rate home loans for individuals generally carry no prepayment penalty under RBI rules, but fixed-rate loans may [VERIFY: current RBI directions]. Read your sanction letter.
- Keep an emergency fund of several months' expenses. Money paid into a home loan is hard to take back out.
- Compare the loan rate with what your money could safely earn. Try the SIP calculator for the investing side, but remember that returns there are not guaranteed.
- If your rate is high, a home loan balance transfer can save more than a small prepayment. Compare in the loan transfer calculator.
- Note the tax effect. Lower interest means a smaller interest deduction, though the saving is usually bigger than the tax lost (home loan tax benefits).
Tip: after every part payment, ask for an updated repayment schedule and check the new end date. Some borrowers find the EMI was reduced when they wanted the tenure shortened.
If your loan floats with the market, your numbers move too. The difference between fixed and floating rates matters for prepayment rules, and the interest rate guide explains how rates change.
A simple decision rule
Prepay when three things are true: you have an emergency fund, no higher-cost debt such as a credit card or personal loan, and a surplus that isn't needed in the next few years. Then keep the EMI, shorten the tenure and prepay early. Run your own figures on the Pulse home loan page before you decide, and speak to a financial adviser or CA if the amounts are large.
Frequently asked questions
Is it better to prepay a home loan or invest the money?
It depends on your loan rate, the safe returns you can get after tax, and how much risk you can take. A prepayment earns a guaranteed saving equal to your loan rate. Investing can earn more or less. Keep an emergency fund either way. This is general information, not personal advice.
Does prepaying a home loan reduce the EMI or the tenure?
Either, depending on the option you choose with the lender. If you keep the EMI the same, the loan ends sooner, which usually saves the most interest. If you ask to lower the EMI, the tenure stays put and monthly relief rises. Confirm the option in writing.
Is there a penalty for part-prepaying a home loan?
On floating-rate home loans taken by individuals, lenders generally cannot charge a prepayment penalty under RBI rules. Fixed-rate loans and loans taken through a company can attract charges. Check your sanction letter. [VERIFY: current RBI directions]
How much should I prepay each year?
There is no fixed number. A common approach is to put any surplus after your emergency fund and other goals into the loan, in one lump sum each year or as a small monthly top-up. Even ₹2,000 to ₹5,000 a month makes a visible difference.
Does prepayment affect my home loan tax benefit?
Yes, it can. The principal you repay counts within its deduction limit, and prepaying lowers the interest you pay, so the interest deduction shrinks as well. The tax saving is small compared with the interest you save. [VERIFY: current provisions under the Income-tax Act, 2025]
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.


Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.