New Launch - India Real Estate Report 2026.
Services
Knowledge Hub
Resources
Tools
Ask Pulse Ai
Services
FOR BUYERS & RENTERS
FOR REAL ESTATE DEVELOPERS

Refer other Connectors &
Multiply IncomeRefer other Connectors
& Multiply Income
Refer KuberX & earn
commission on every
loan they get
disbursed.


Scan & Download
©PropTech Pulse 2025, All rights reserved.


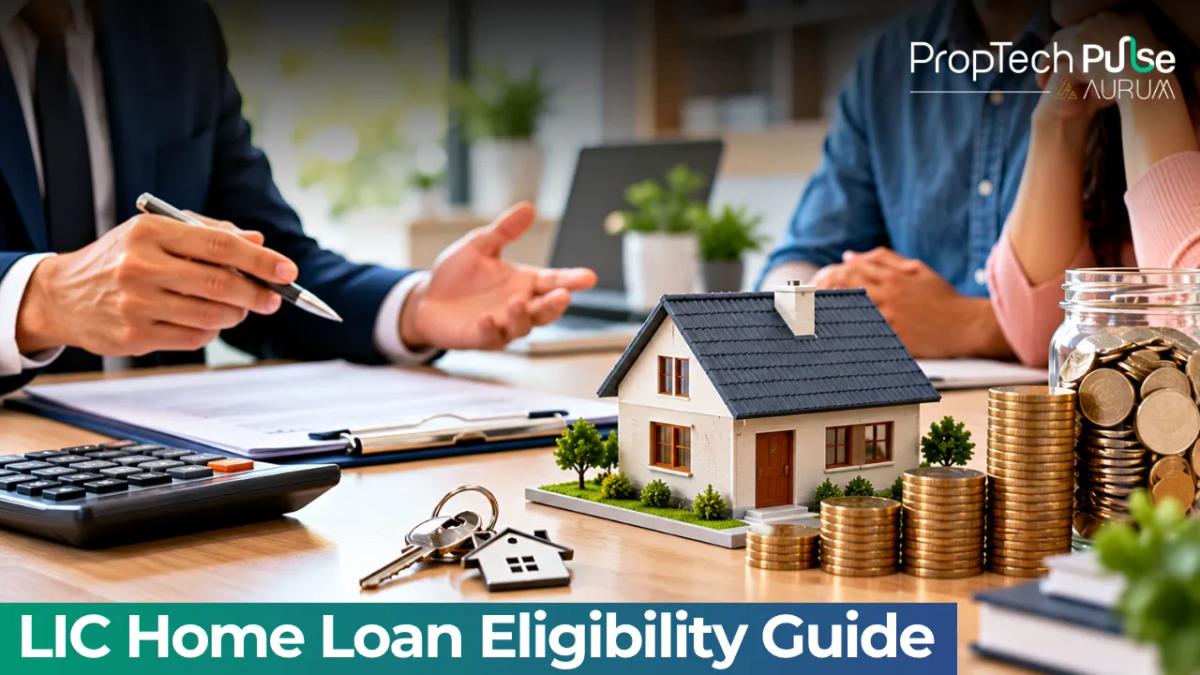
With LIC Housing Finance, your eligibility comes down to one number: how much EMI the lender believes you can carry. Age, income, existing loans and credit score all feed that number, and it decides the loan amount, not the salary slip alone.
Below is what LIC home loan eligibility usually looks at, an example showing how age and income change the amount, the documents to keep ready, and how to lift your eligibility before you apply. LIC Housing Finance is a housing finance company, separate from the insurer that shares its name.
LIC home loan eligibility criteria
Quick answer
To qualify for an LIC Housing Finance home loan you need to be an adult with steady income, a decent credit score (around 700 or above), and enough repayment capacity after existing EMIs. Age, work history and the property's value set your maximum loan amount and tenure.
| Factor | Typical requirement | Why it matters |
|---|---|---|
| Age | About 23 years minimum; up to about 60 for salaried and 75 for self-employed, at loan maturity or application | Age caps your tenure, and so your loan amount |
| Minimum income | Around ₹25,000 a month salaried; ₹50,000 self-employed | A guide, not a guarantee; the lender looks at total repayment capacity |
| Credit score | About 700 or above | A higher score can help with the rate |
| Work experience | About 2 years salaried; 3 years self-employed | Job changers may need a longer track record |
| Tenure | Up to 30 years | Shorter if your retirement age is near |
| Loan-to-value | Roughly 60% to 75% of property value on the Pulse page; RBI caps vary by loan size | You fund the rest as down payment |
| EMI-to-income limit | Roughly 60% to 70% listed on the Pulse page | Lower if you already carry EMIs |
Lenders revise criteria often, so treat the figures above as a guide drawn from Pulse's LIC eligibility calculator page and general lender practice. Confirm them on the lender's site or helpline (1800-209-1989) before you apply.
How much you can borrow, with numbers
Lenders work backwards from the EMI you can afford. Take an applicant with a gross monthly income of ₹80,000 and ₹8,000 of existing EMIs. If the lender allows EMIs up to 60% of income, ₹48,000, then ₹40,000 is left for the new loan. At 50%, it's ₹32,000.
Now bring age into it. At 8.5% (an illustrative rate), each ₹1 lakh of loan costs about ₹868 a month over 20 years, but ₹985 over 15 years and ₹1,240 over 10 years. A shorter tenure, forced by an approaching retirement age, cuts your loan amount sharply.
| Tenure | EMI limit 50% | EMI limit 60% |
|---|---|---|
| 20 years | ₹36.9 lakh | ₹46.1 lakh |
| 15 years | ₹32.5 lakh | ₹40.6 lakh |
| 10 years | ₹25.8 lakh | ₹32.3 lakh |
Source: author's calculation using the reducing-balance EMI formula. Rate and EMI-to-income limits are illustrative . Try your own numbers in the home loan eligibility calculator and the LIC home loan EMI calculator.
So a 45-year-old salaried applicant with a 60-year retirement age might qualify for a smaller loan than a 30-year-old with the same salary. It surprises many buyers. The guide to reducing home loan tenure helps you plan the other side, after you've borrowed.
Salaried, self-employed and co-applicants
Salaried
Lenders like a stable employer and a clean salary trail. Recent salary slips, Form 16 and six months of bank statements are the core proof. A recent job change can slow things down if you don't have enough months in the new role.
Self-employed
Income is judged on tax returns, not on what you say you earn. Two or three years of returns, with matching bank statements, count for more than one strong year. Business proof and a balance sheet usually follow.
Co-applicants
Adding a spouse, parent or sibling with income raises the EMI limit, so the loan can be bigger. Their credit score counts too. For ownership questions, see joint ownership of property.
Check your eligibility in five steps
- Add up your gross monthly income and every existing EMI, including credit card minimums.
- Multiply income by the EMI-to-income limit you expect (start with 50% to be safe), then subtract existing EMIs.
- Divide the EMI you have left by the EMI per lakh for your tenure, then multiply by ₹1 lakh. That gives a rough loan amount.
- Cross-check it in LIC Housing Finance's own eligibility calculator, which asks for income, current EMIs, rate and term.
- Compare the amount with the loan-to-value cap on the flat you like. The lower of the two is your real limit.
Sanction still depends on the property. The lender's lawyer checks the title and a valuer checks the price, so read the property legal verification guide before you pay a token amount. And remember that a fixed number on paper can move with the rate.
Documents to keep ready
Identity and address proof (PAN, Aadhaar), income proof (salary slips, Form 16 or returns), employment or business proof, bank statements, and the property papers. The full list is in the home loan documentation checklist. If the flat is still under construction, ask the builder for the RERA registration too (RERA).
Keep your credit report clean before you apply. Read the CIBIL score guide and check your CIBIL score.
How to raise your eligibility
- Pay off small loans first. A ₹6,000 personal loan EMI can cost you about ₹7 lakh of borrowing power at these rates, since each ₹868 of EMI supports ₹1 lakh.
- Add an earning co-applicant.
- Choose the longest tenure your age allows, then prepay. LIC Housing Finance says on its website that its home loans have no prepayment charges .
- Raise your down payment, since the loan-to-value cap limits the loan whatever your income.
- Improve your credit score for a few months first.
Tip: eligibility is not affordability. The most you can borrow is often more than you should. Keep total EMIs near 40% of take-home pay, and compare rates using the home loan interest rate guide and fixed vs floating rates.
Before you apply
Work out your EMI limit first, then the loan it supports at your age. Check your credit report, clear small loans and add a co-applicant if you need one. Then compare LIC Housing Finance with at least one bank on rate, fees and prepayment terms. The Pulse home loan page is a good place to start.
Frequently asked questions
What is the minimum salary for an LIC home loan?
LIC Housing Finance decides on your overall repayment capacity rather than one fixed salary. Pulse's LIC eligibility page lists ₹25,000 a month for salaried and ₹50,000 for self-employed applicants, but confirm this with the lender before you rely on it.
What CIBIL score do I need for an LIC home loan?
A score of about 700 or above is the usual comfort zone for housing finance companies, and a higher score helps with the rate. A lower score does not always mean rejection, but expect closer checks. Check your own report first.
Can I get an LIC home loan without a salary slip?
Self-employed applicants apply on income tax returns, bank statements and business proof instead of salary slips. Salaried applicants without slips can sometimes use bank statements and Form 16, at the lender's discretion. Ask the branch which alternative documents it accepts.
Does LIC Housing Finance charge for prepayment?
LIC Housing Finance's website says its home loans carry no prepayment charges. Confirm this for your loan type in the sanction letter, because the rule depends on whether the rate is floating and who the borrower is.
How can I increase my LIC home loan eligibility?
Add an earning co-applicant, clear existing EMIs, choose the longest tenure your age allows, and raise your credit score before applying. Each of these lifts the EMI you can carry, which is what drives the loan amount.
Enjoyed this blog article? Visit PropTech Pulse for more interesting blogs.


Ask Pulse Ai anything about real estate
Unlock the Latest in Real Estate
News, Infographics, Blogs & More! Delivered to your inbox.